Product development from releasing MVP to polishing it continually. Scaled a seller-lending product from 10K to 120K users in 6 months, then lifted activation conversion from 52% to 62%
My Role: UX/UI Designer
Duration: Jun'22 – Feb'23 (8 months)
Cooperated with multiple teams (PM, BD, CX, Finance, MKT)
As part of business expansion, the BD team identifies the need for such a business loan after launching a personal loan. Typically business loans will always be a productive product. Due to its large amount, it can expect lower interest rates than other types.
It is a win-win business. Seller applied loan for their business expansion, eventually the profit will return to the seller, and then they can repay to Shopee. So for us, loan is a good opportunity to size our revenue.
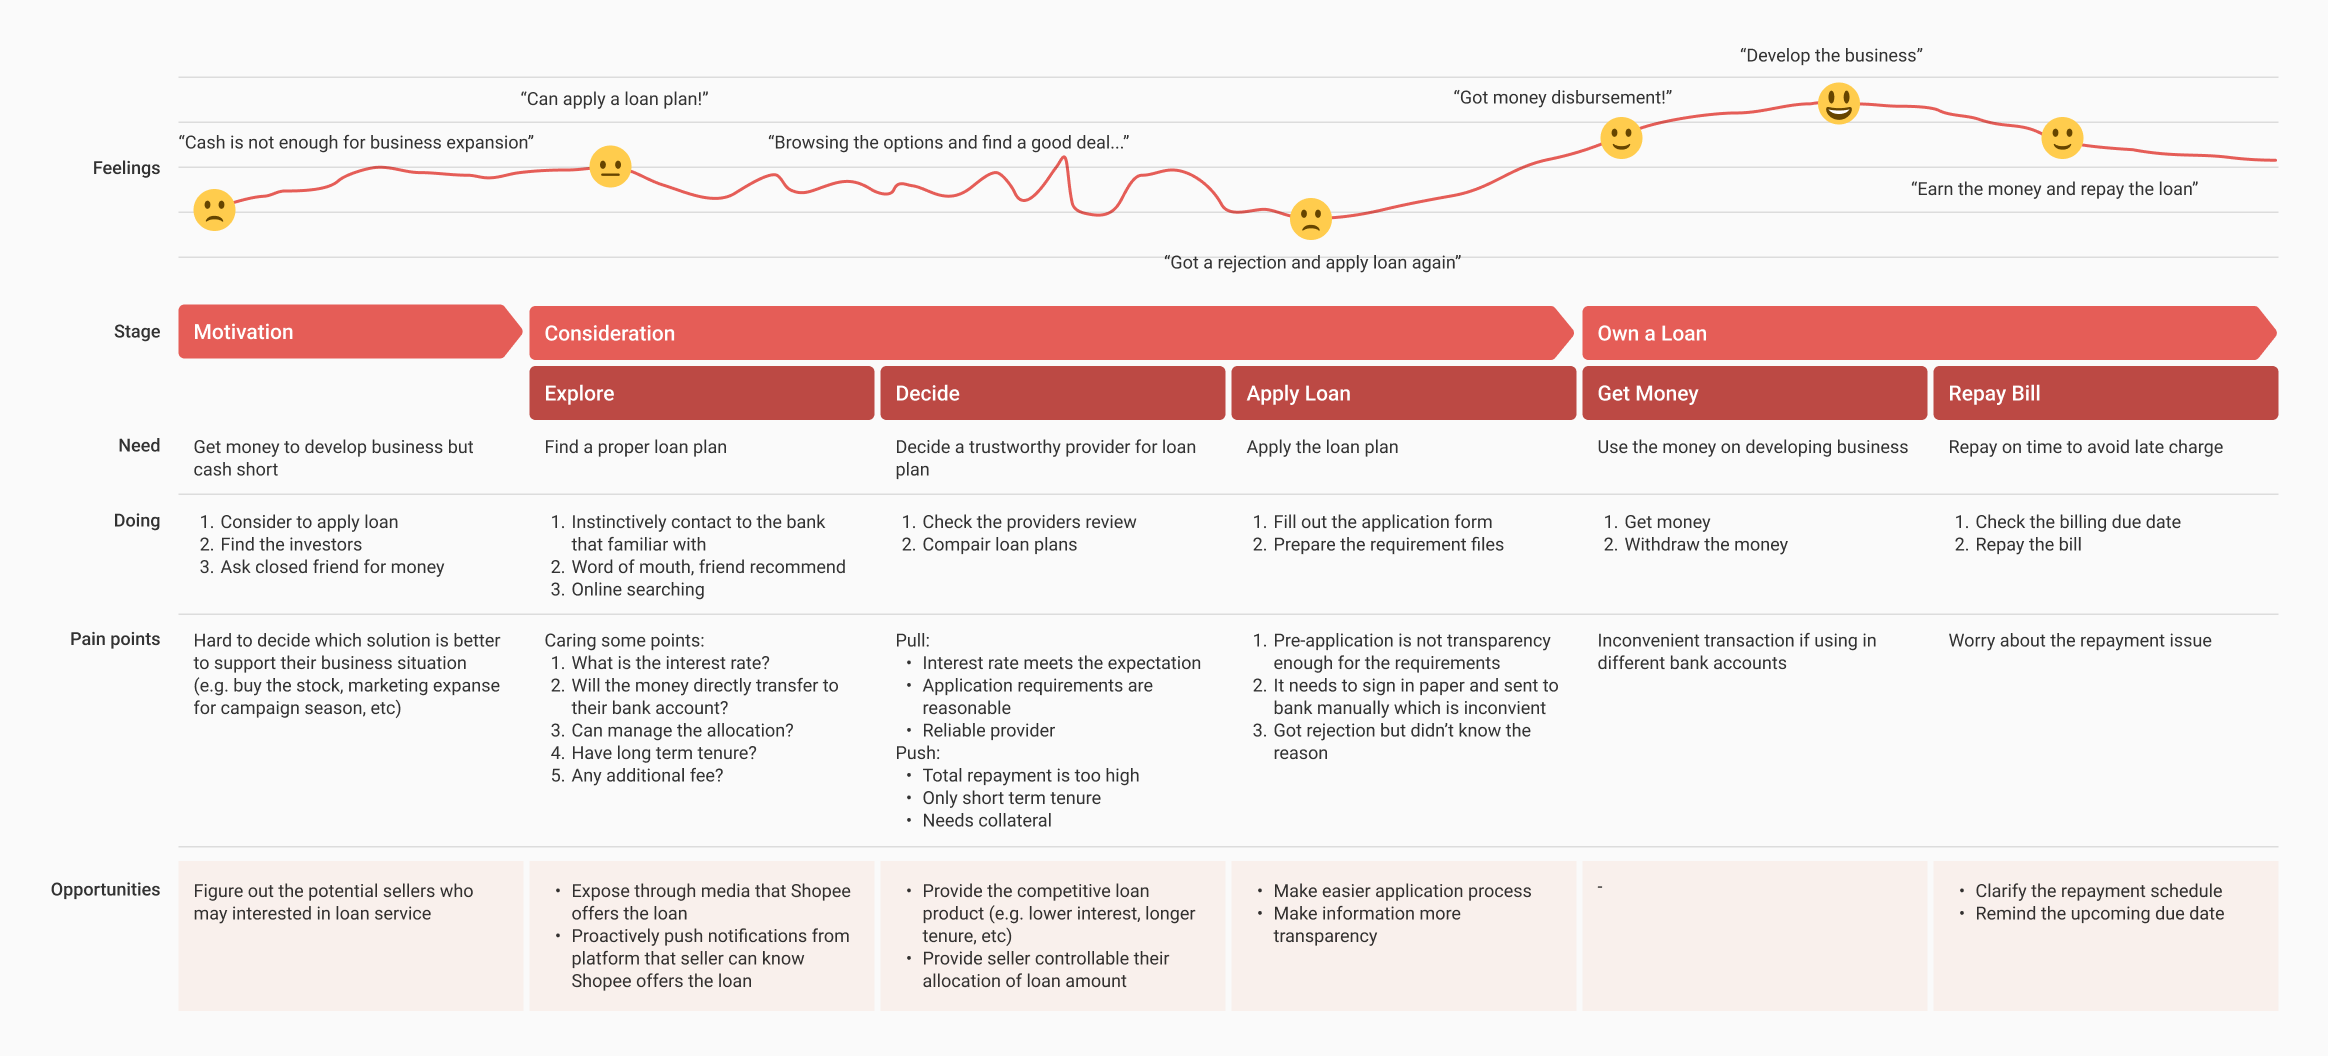
It’s lucky that we can reach out to our target users, Shopee sellers. I got the data through a phone call interview (supported by CX team) with 16 sellers in 3 groups based on their NMV (Net Merchandise Value) size.
To better share the interview results with the team and make it easier to understand, I map out this user journey to reveal users’ pain points and how their attitudes change over time. It helps us consider the main features of MVP to develop a solution with high CLV (Customer Lifetime Value).
The major loan provider was banks. At that time, the business loan provider from the financial company of e-commerce in IT was only Tokopedia and the proportion of users compared to banks was pretty small.
To make decisions based on knowledge of what is currently working well for users, and use the insights to add value to our product, we do the competitor analysis in two aspects:
Define the loan product details, like tenure, the range of loan amount, the competitive interests, additional fees, billing rules, etc.
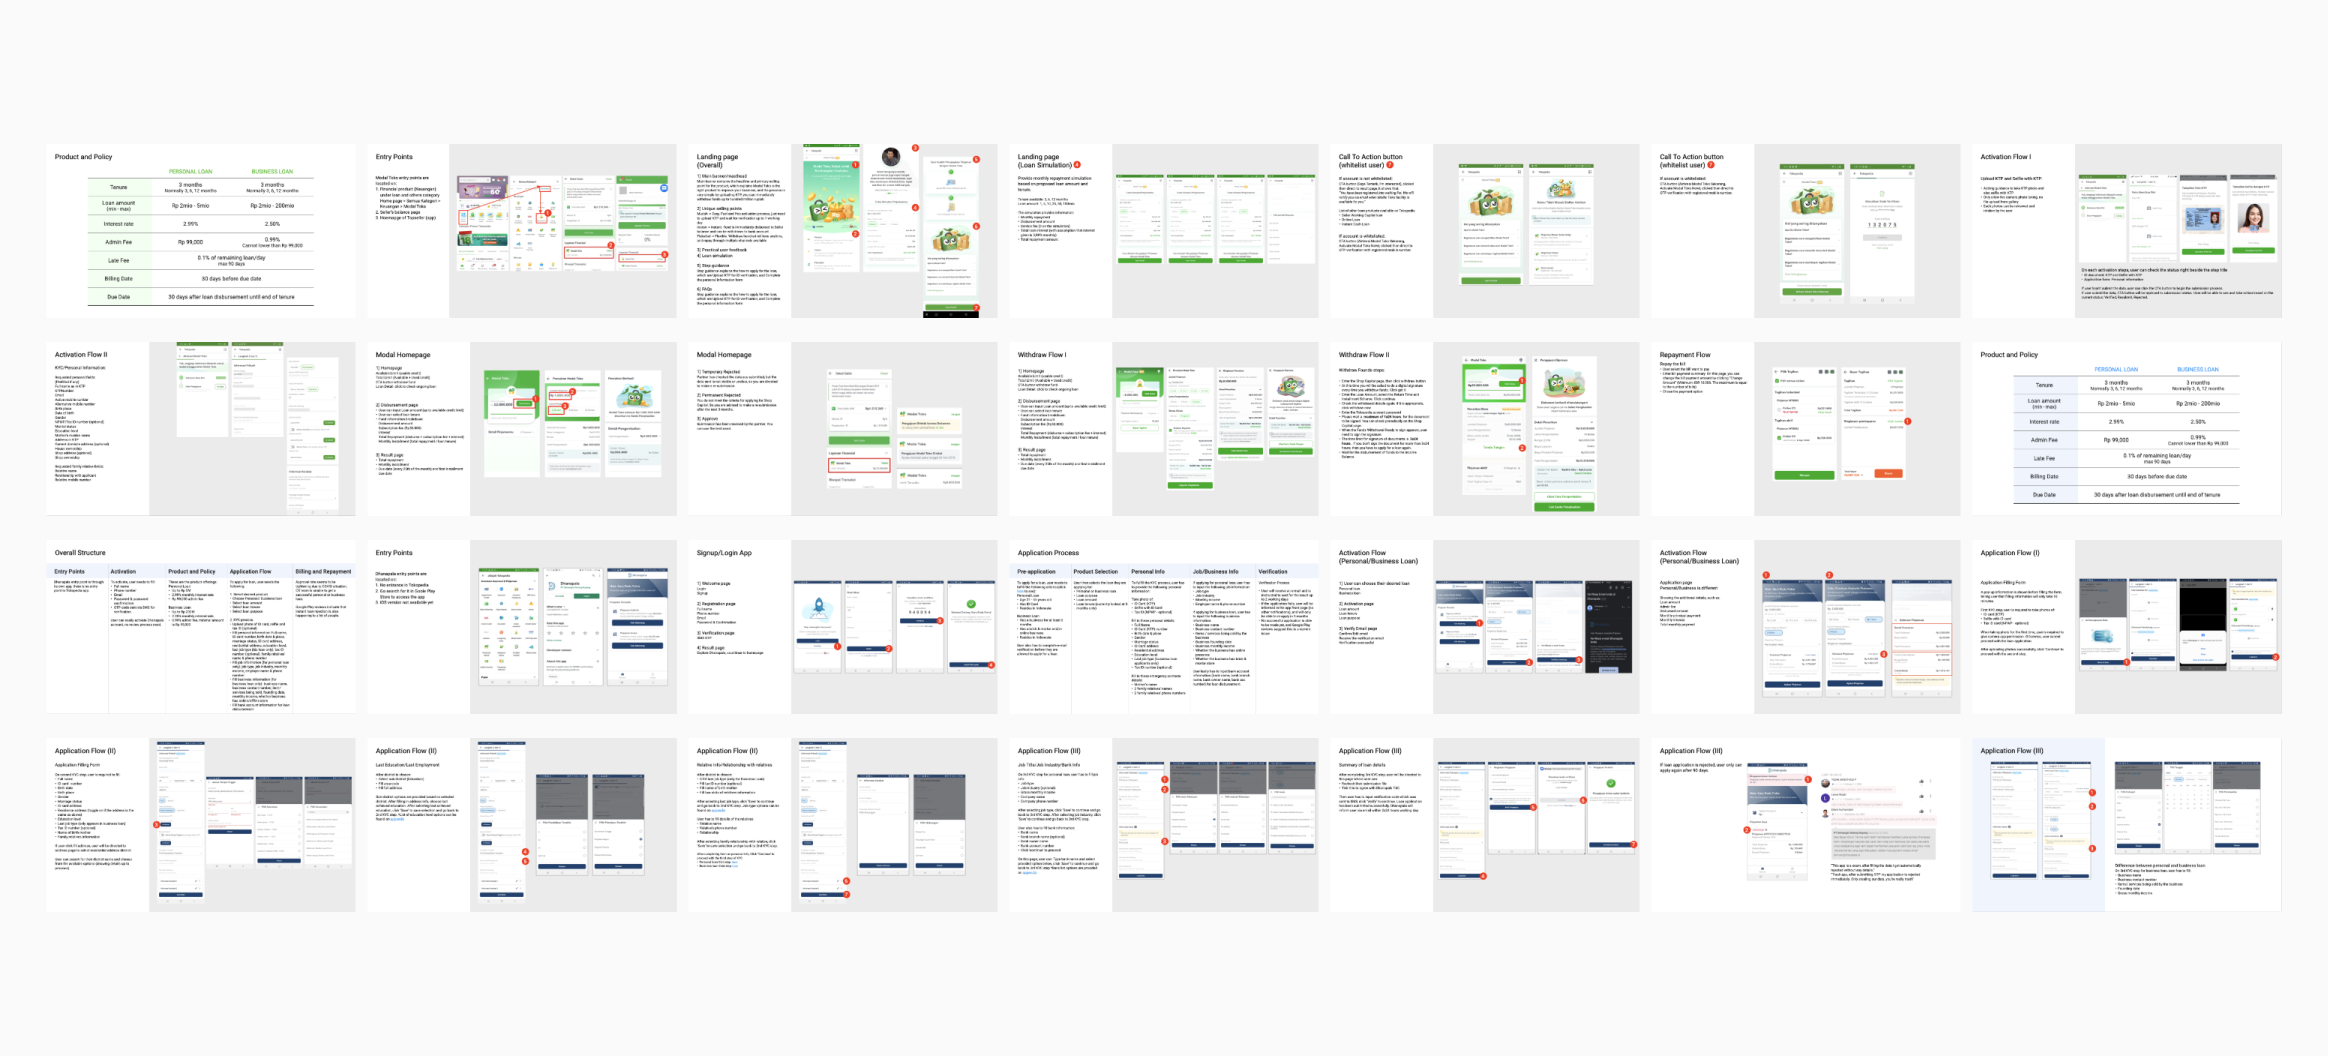
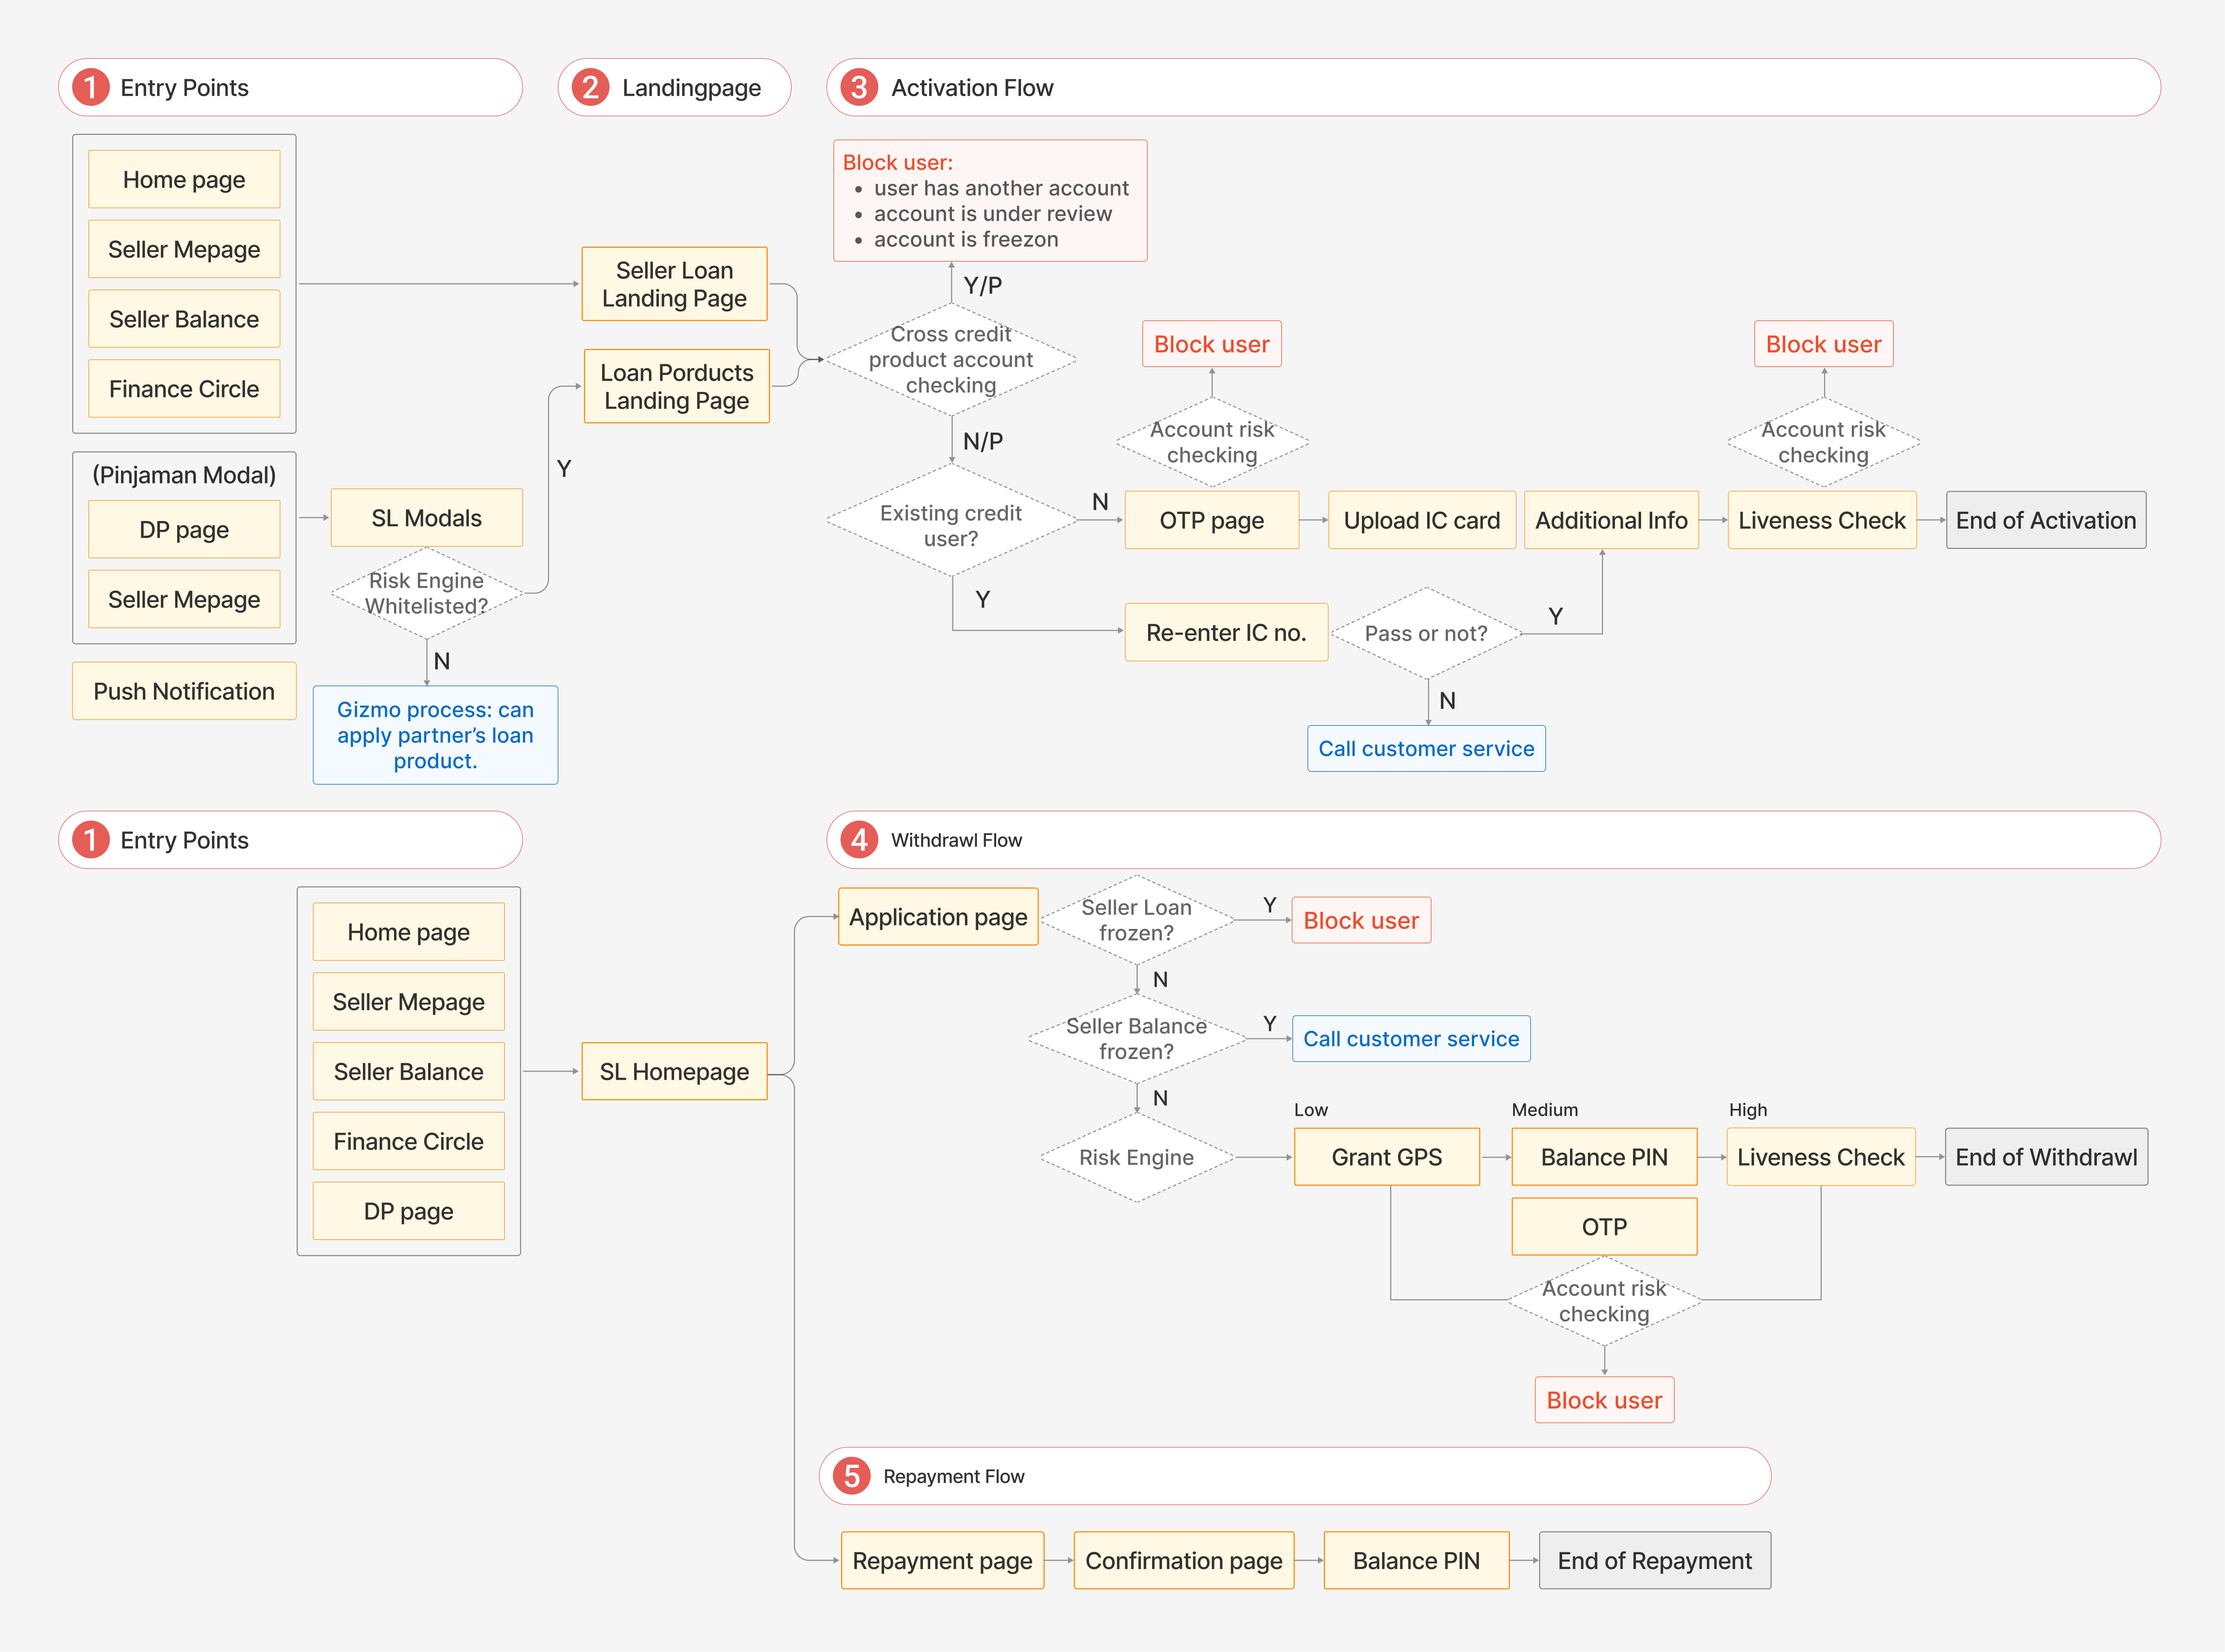
It is challenging to prioritize the product features involving many stakeholders. The flowchart helps us to align everyone’s expectations efficiently. It is an easy-to-understand map to plot interactive sequences and easy to erase and redraw while bouncing ideas around. Here is the overall flow of 5 key objectives and interactions.
After wrapping up the research and establishing a direction, we set 4 design principles that we want to achieve. These principles served as the foundation for the whole team and helped me focus on the most important.

Ensure the numbers are competitive, the calculation details are transparent, and the terms are easy to understand.
Sellers are sensitive to the price. They are interested in the best deal and care about the numbers.

Ensure the processes are accessible and efficient.
Our advantage over banks is that sellers can reach us online and do things by themselves. They do not need to find a bank teller or send the paperwork.

Ensure small details like transparency, assurance, safety, and so on can communicate trustworthiness well through design.
Building trust with users is a gradual and consistent process. It is embedded in every single interaction that users experience over a set of encounters.

Ensure the friction impedes users momentarily, but not overall experience.
The friction is a way not only to protect users on occasions but also to secure the platform itself.
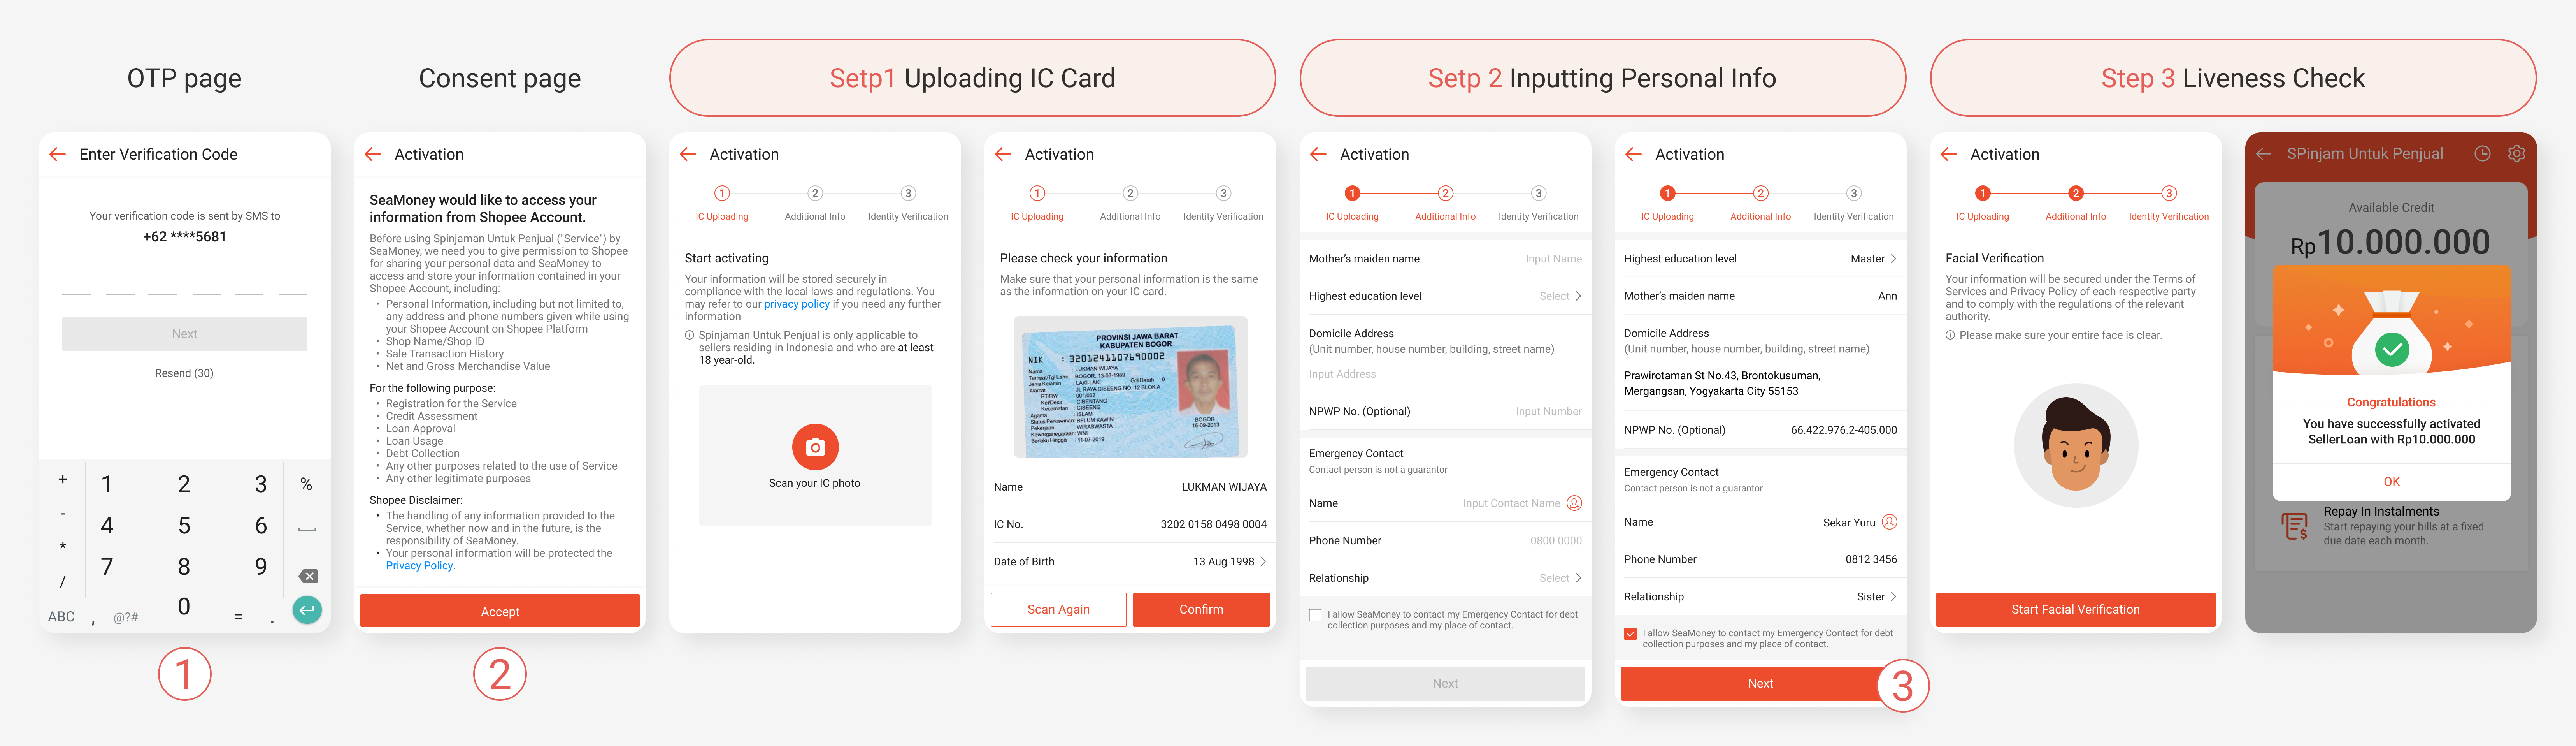
Refine the activation flow into 3 key steps: uploading IC Card, inputting personal info, and liveness check.
IC and personal information are n important data to verify users and comply with the local regulation. It processes ID KTP verification and OJK SLIK (debtor information system) checking. Liveness check is an anti-spoofing method for security purposes.
Before that, we set an OTP page which is proved that can filter out up to 60% of fraud or unserious users.
A grant data permission page for privacy awareness. It has the benefit to prefill or create the account automatically by sharing and building users’ data.
To explicit permission from users, here used the checkbox that users need to do an action instead of an unrealized grant by clicking the next button.
It is crucial to filter or even block the fraud user. Withdrawal makes money transactions. We planned a protection mechanism triggered by the risk level and process tracing, checking, and verifying
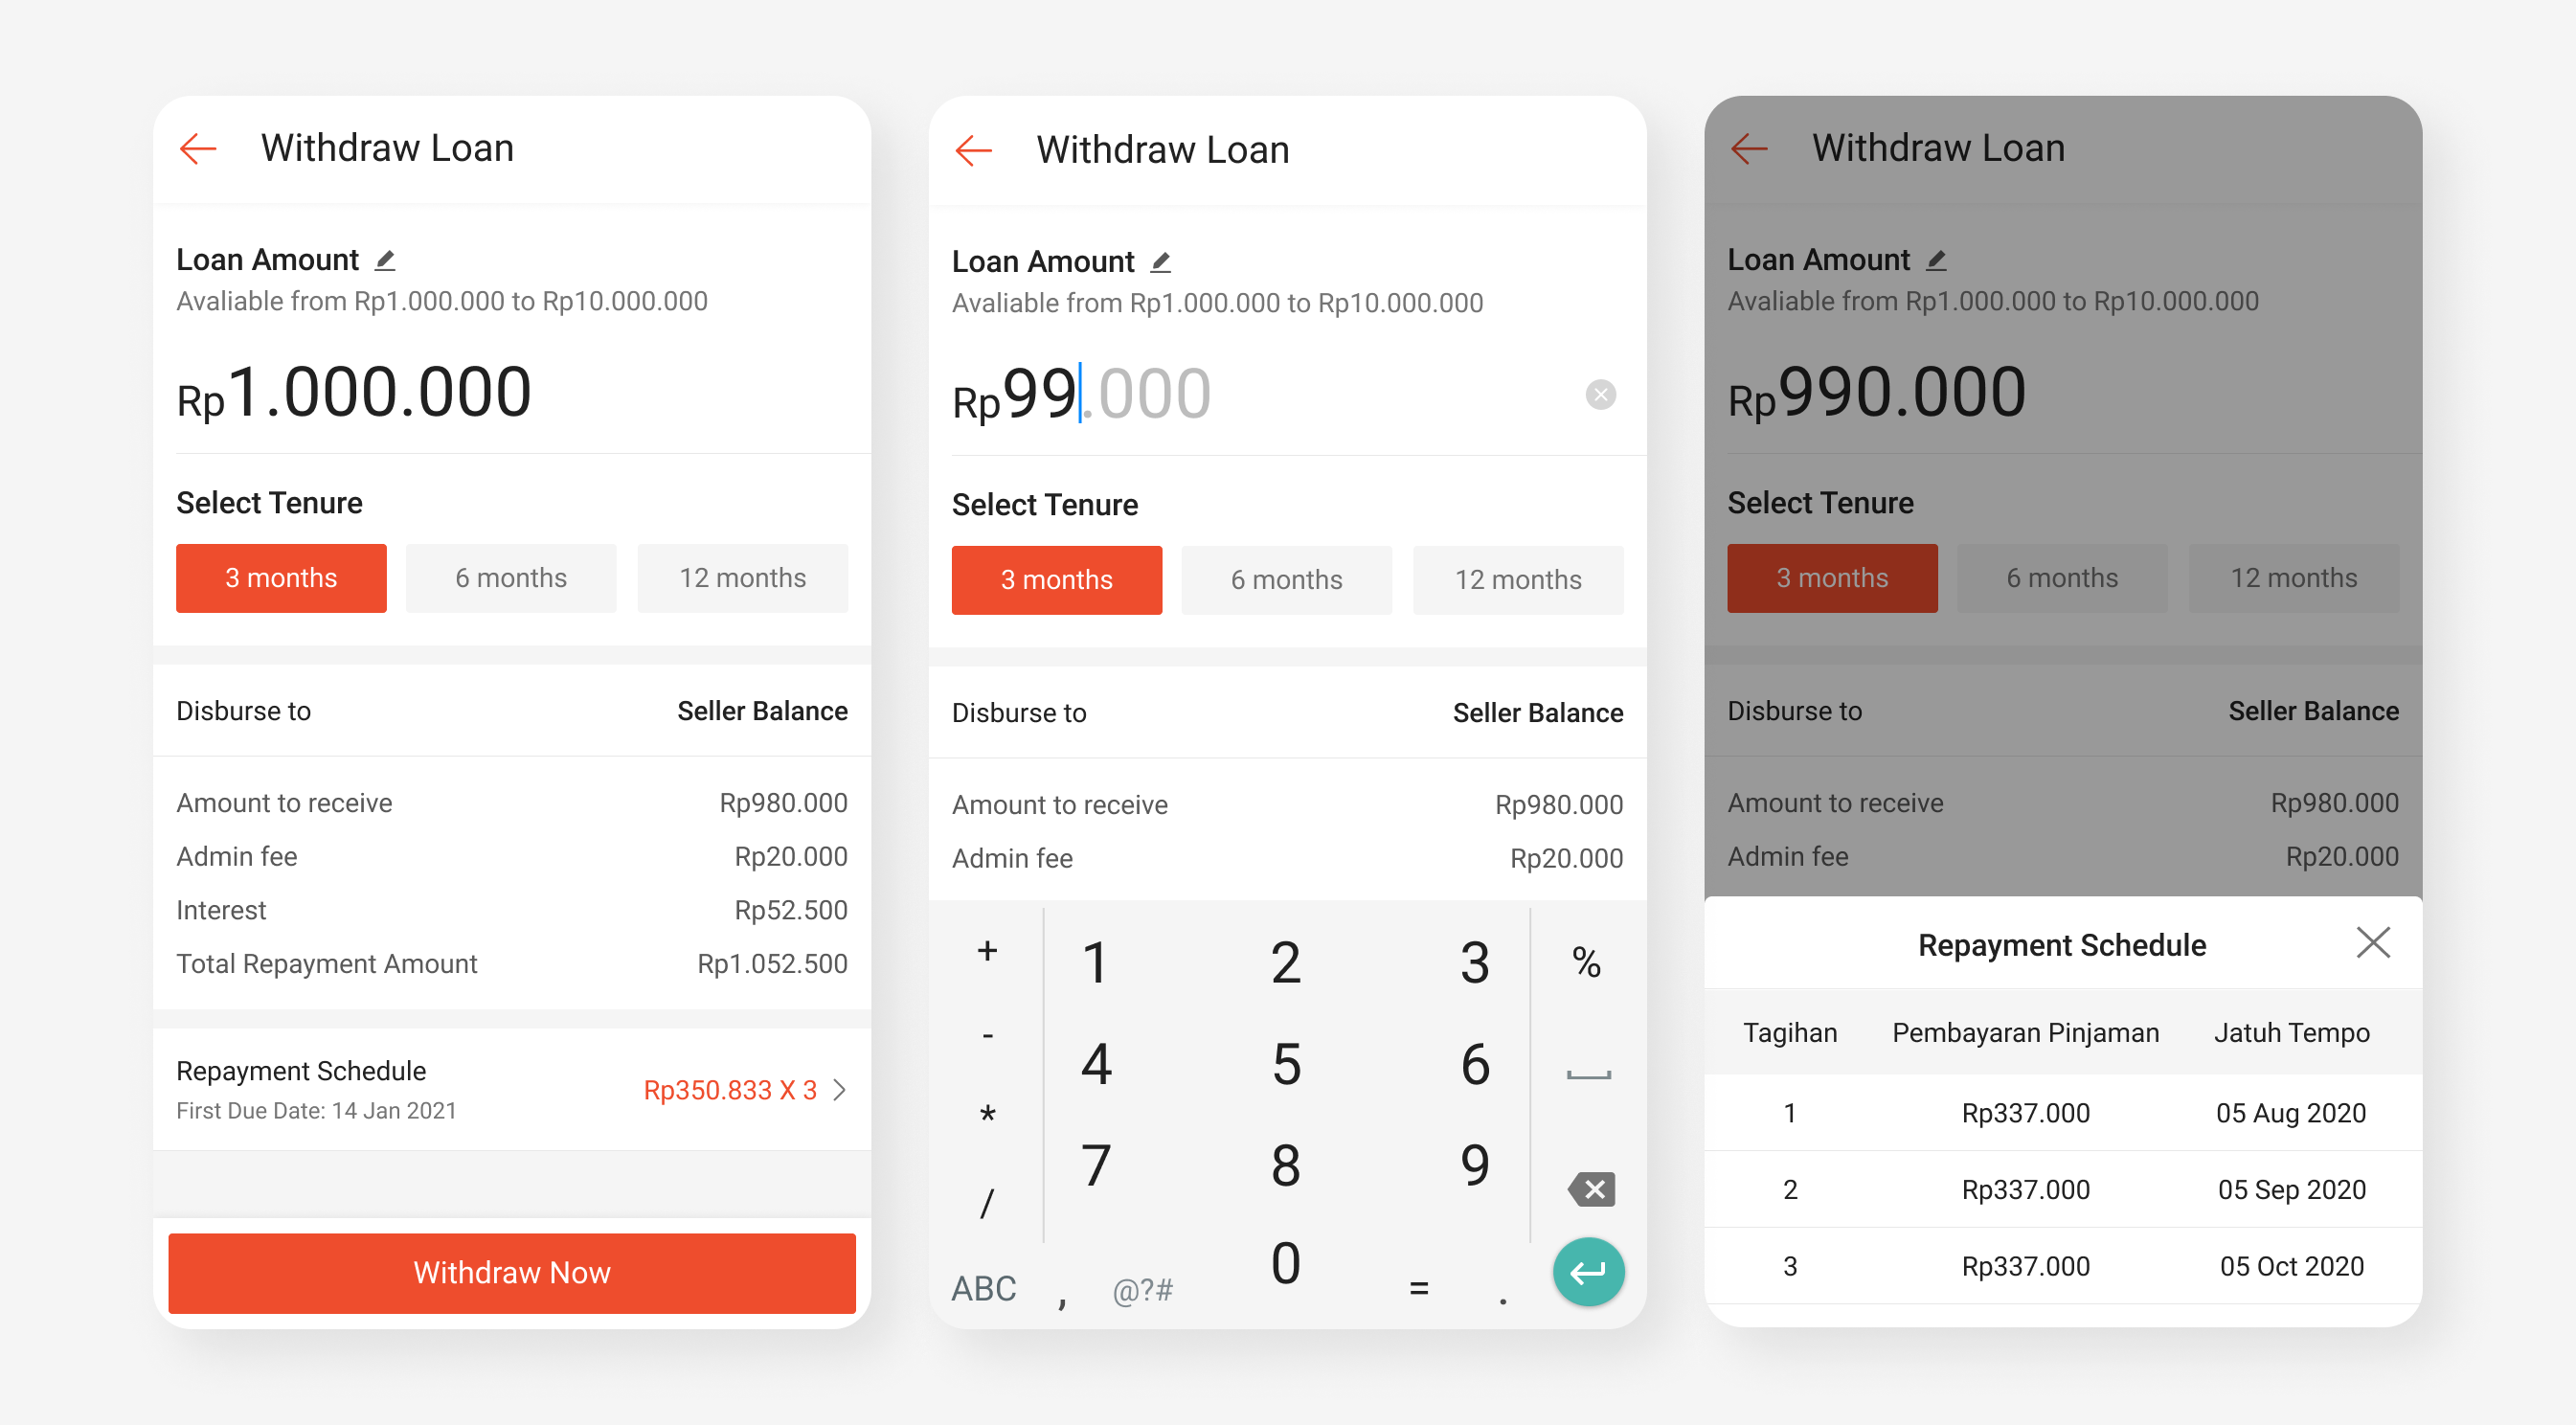
Sellers seek to allocate the loan period and amount by themselves. We allow users to input any amount in a limit range and provide tenure options for flexibility
Sellers care about the best deal and number. We break down the statement for each amount with a straightforward title and provide a repayment schedule.
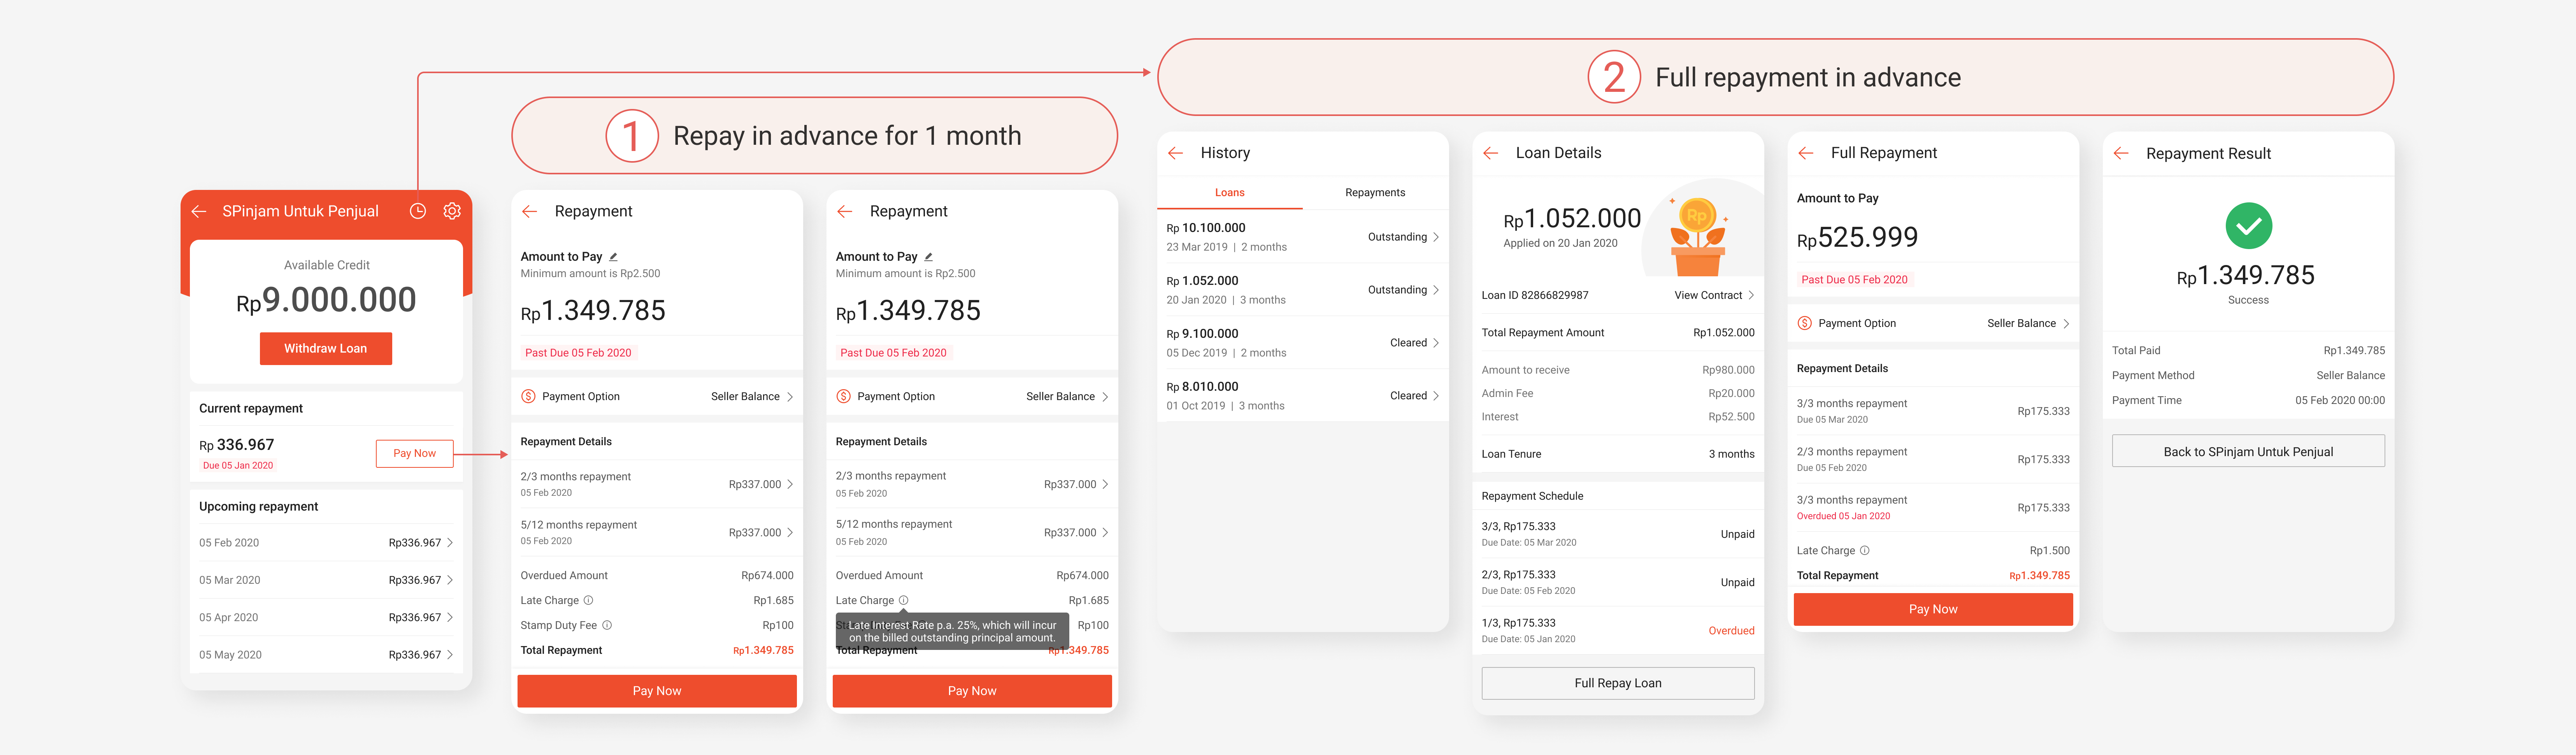
Users can do the partial repayment before the due date and what payment method they preferred. Users will know precisely what are doing with their money without worrying about making a mistake.
Repay in advance is a flexible repayment option that the user expected. However, it conflicts with platform profit. Here is a design to control both sides.
Repay in advance for 1 month. We offer the service that users can pay the bill for a further month but weaken it with plain visuals.
Set a long path to make it hard to reach. If users want to fully repay the bill in advance, they can go through: History -> Loan -> Loan details -> Scroll down to see the fully repay button.

With the help of Shopee Loan for Sellers, my original order of 300-400 per month has now reached 2,000! Very helpful in developing business.

Shopee Loan for Sellers helps me create new markets, increase stock, and increase my store turnover. Thank you, Shopee!

The interest is low and the application process is instant. The payment process is also directly carried out via the Shopee.
Grow to around 12W after 6 months later
Get 10% market share in all loan provider; 60% market share in e-commerce loan provider
More than half of the users with no difficulty using the product. Spending time inactivation flow is less than 7 mins. 16% of seller users are open to using.
Achieved the expect revenue
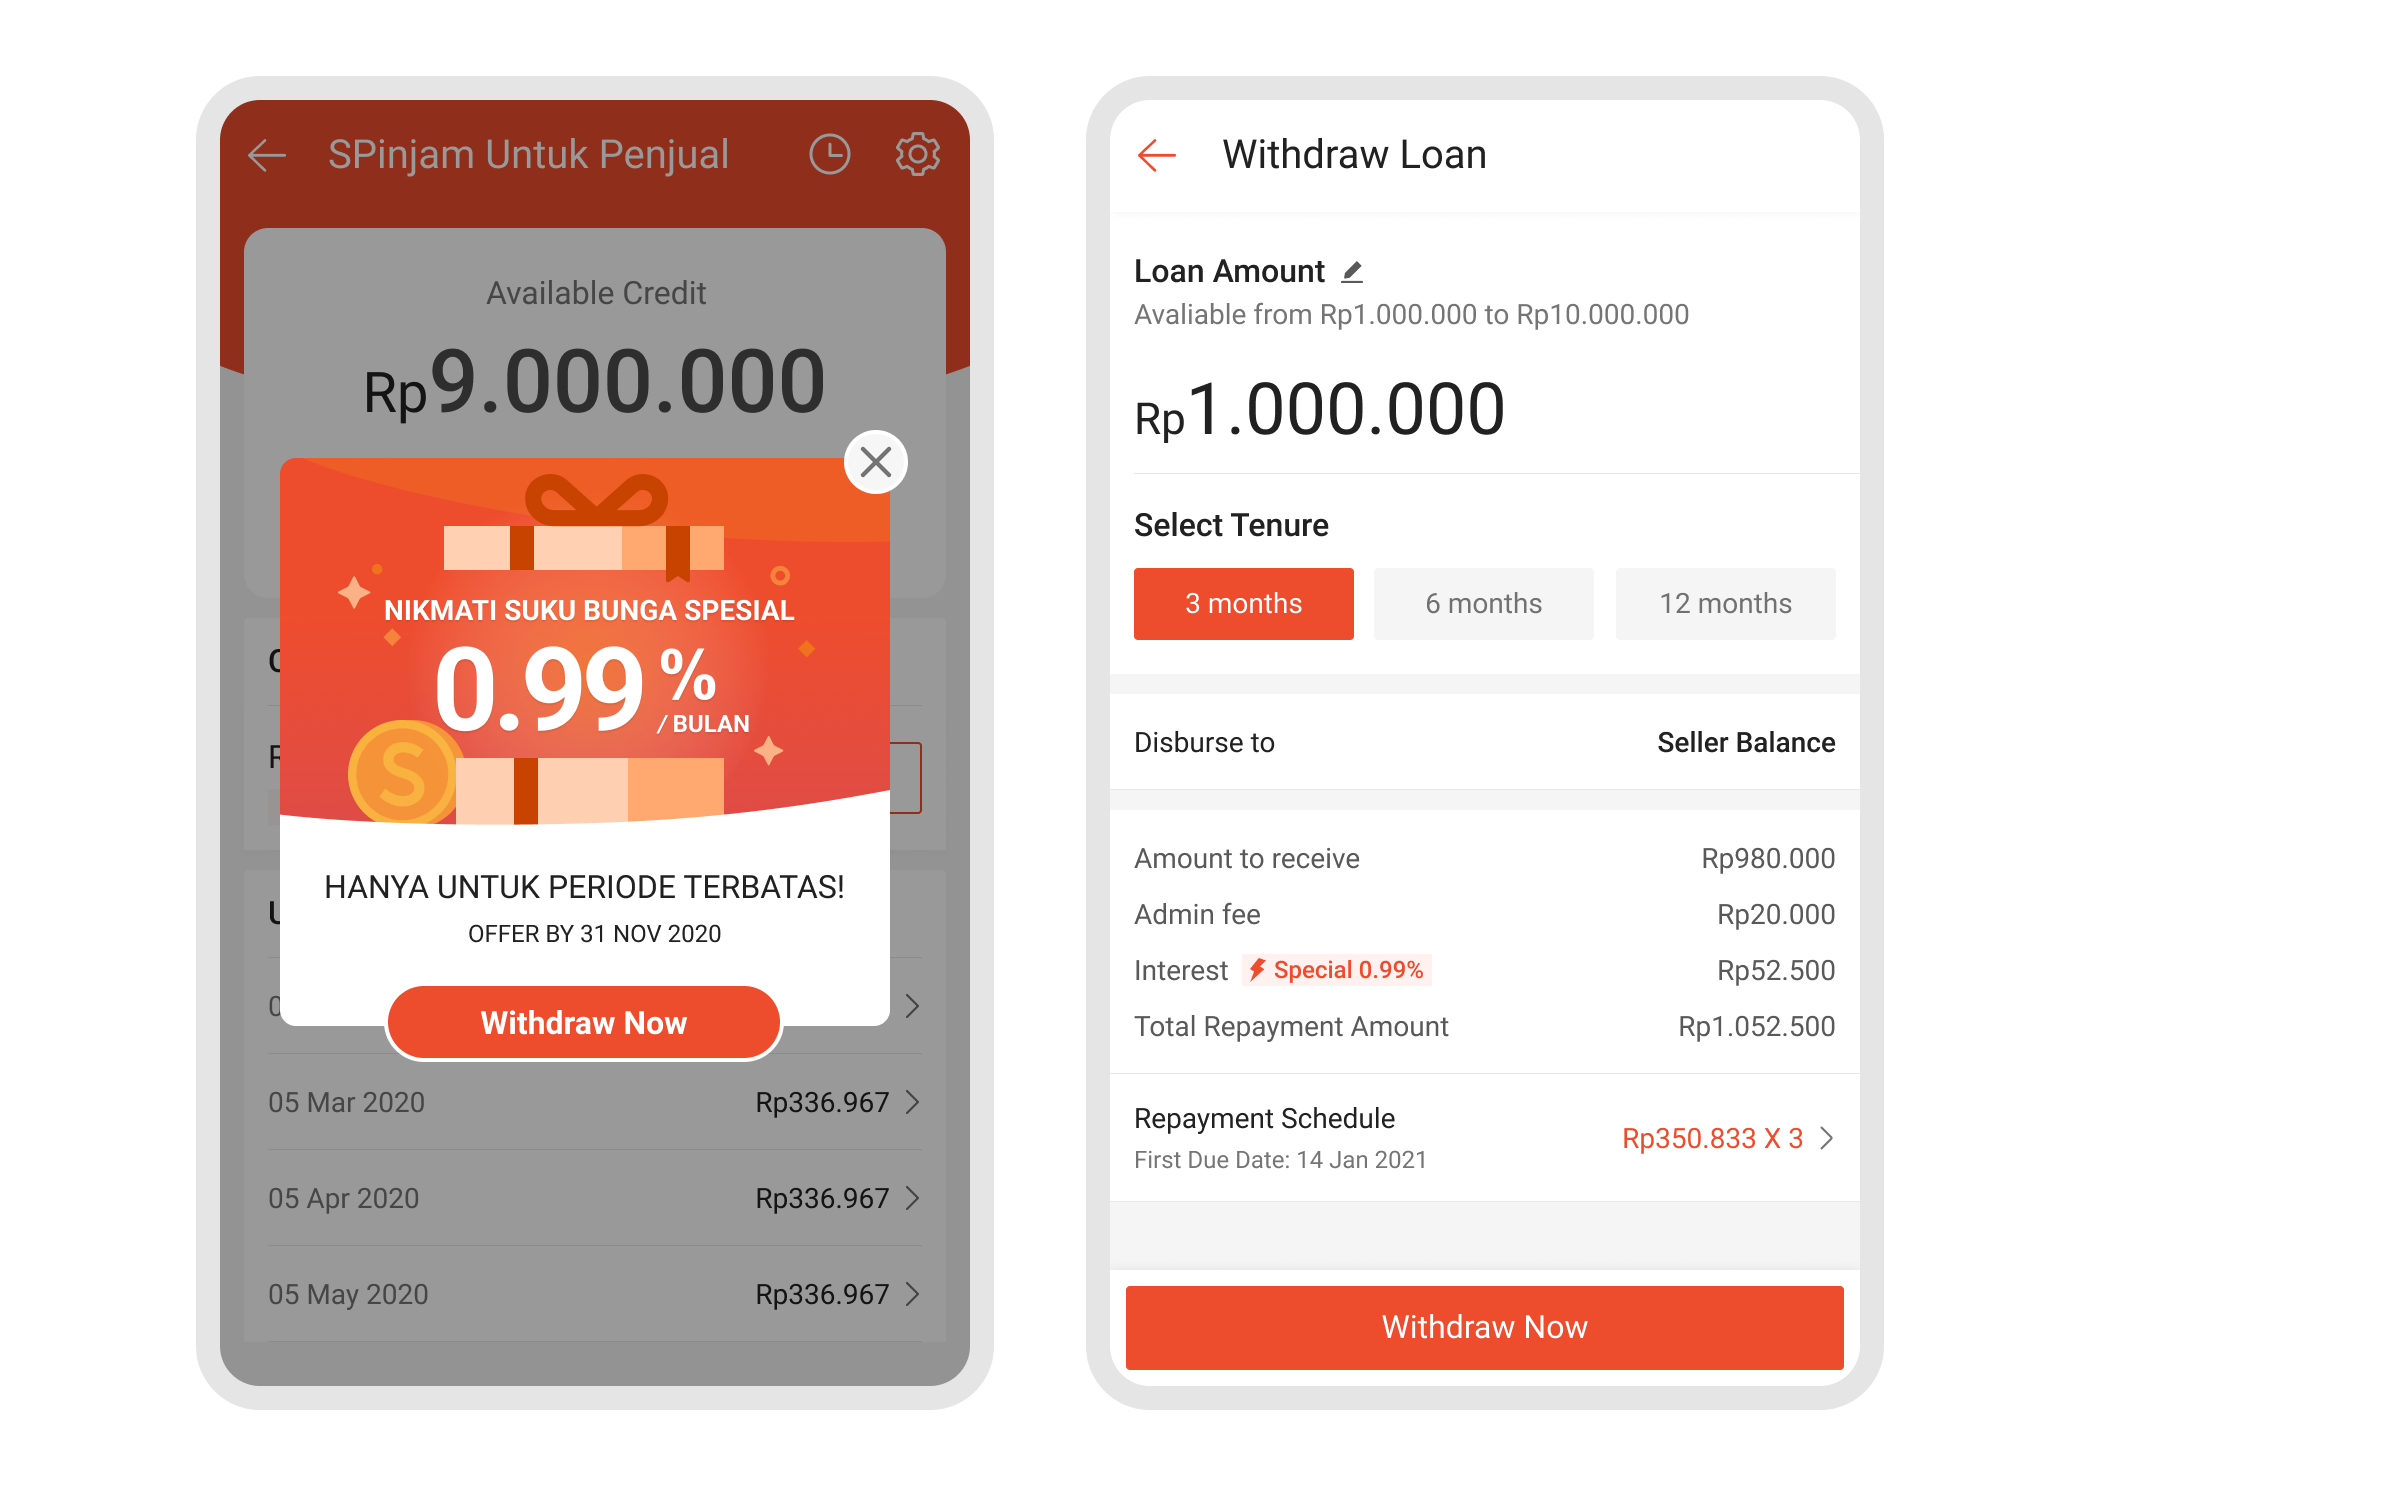
From the user survey, the interest rate influenced sellers' willingness to apply for loans. Most sellers who have sufficient funding mentioned that they are open to using loans if we offer a lower interest rate. We conducted several rounds of campaigns to increase the activation completion rate.
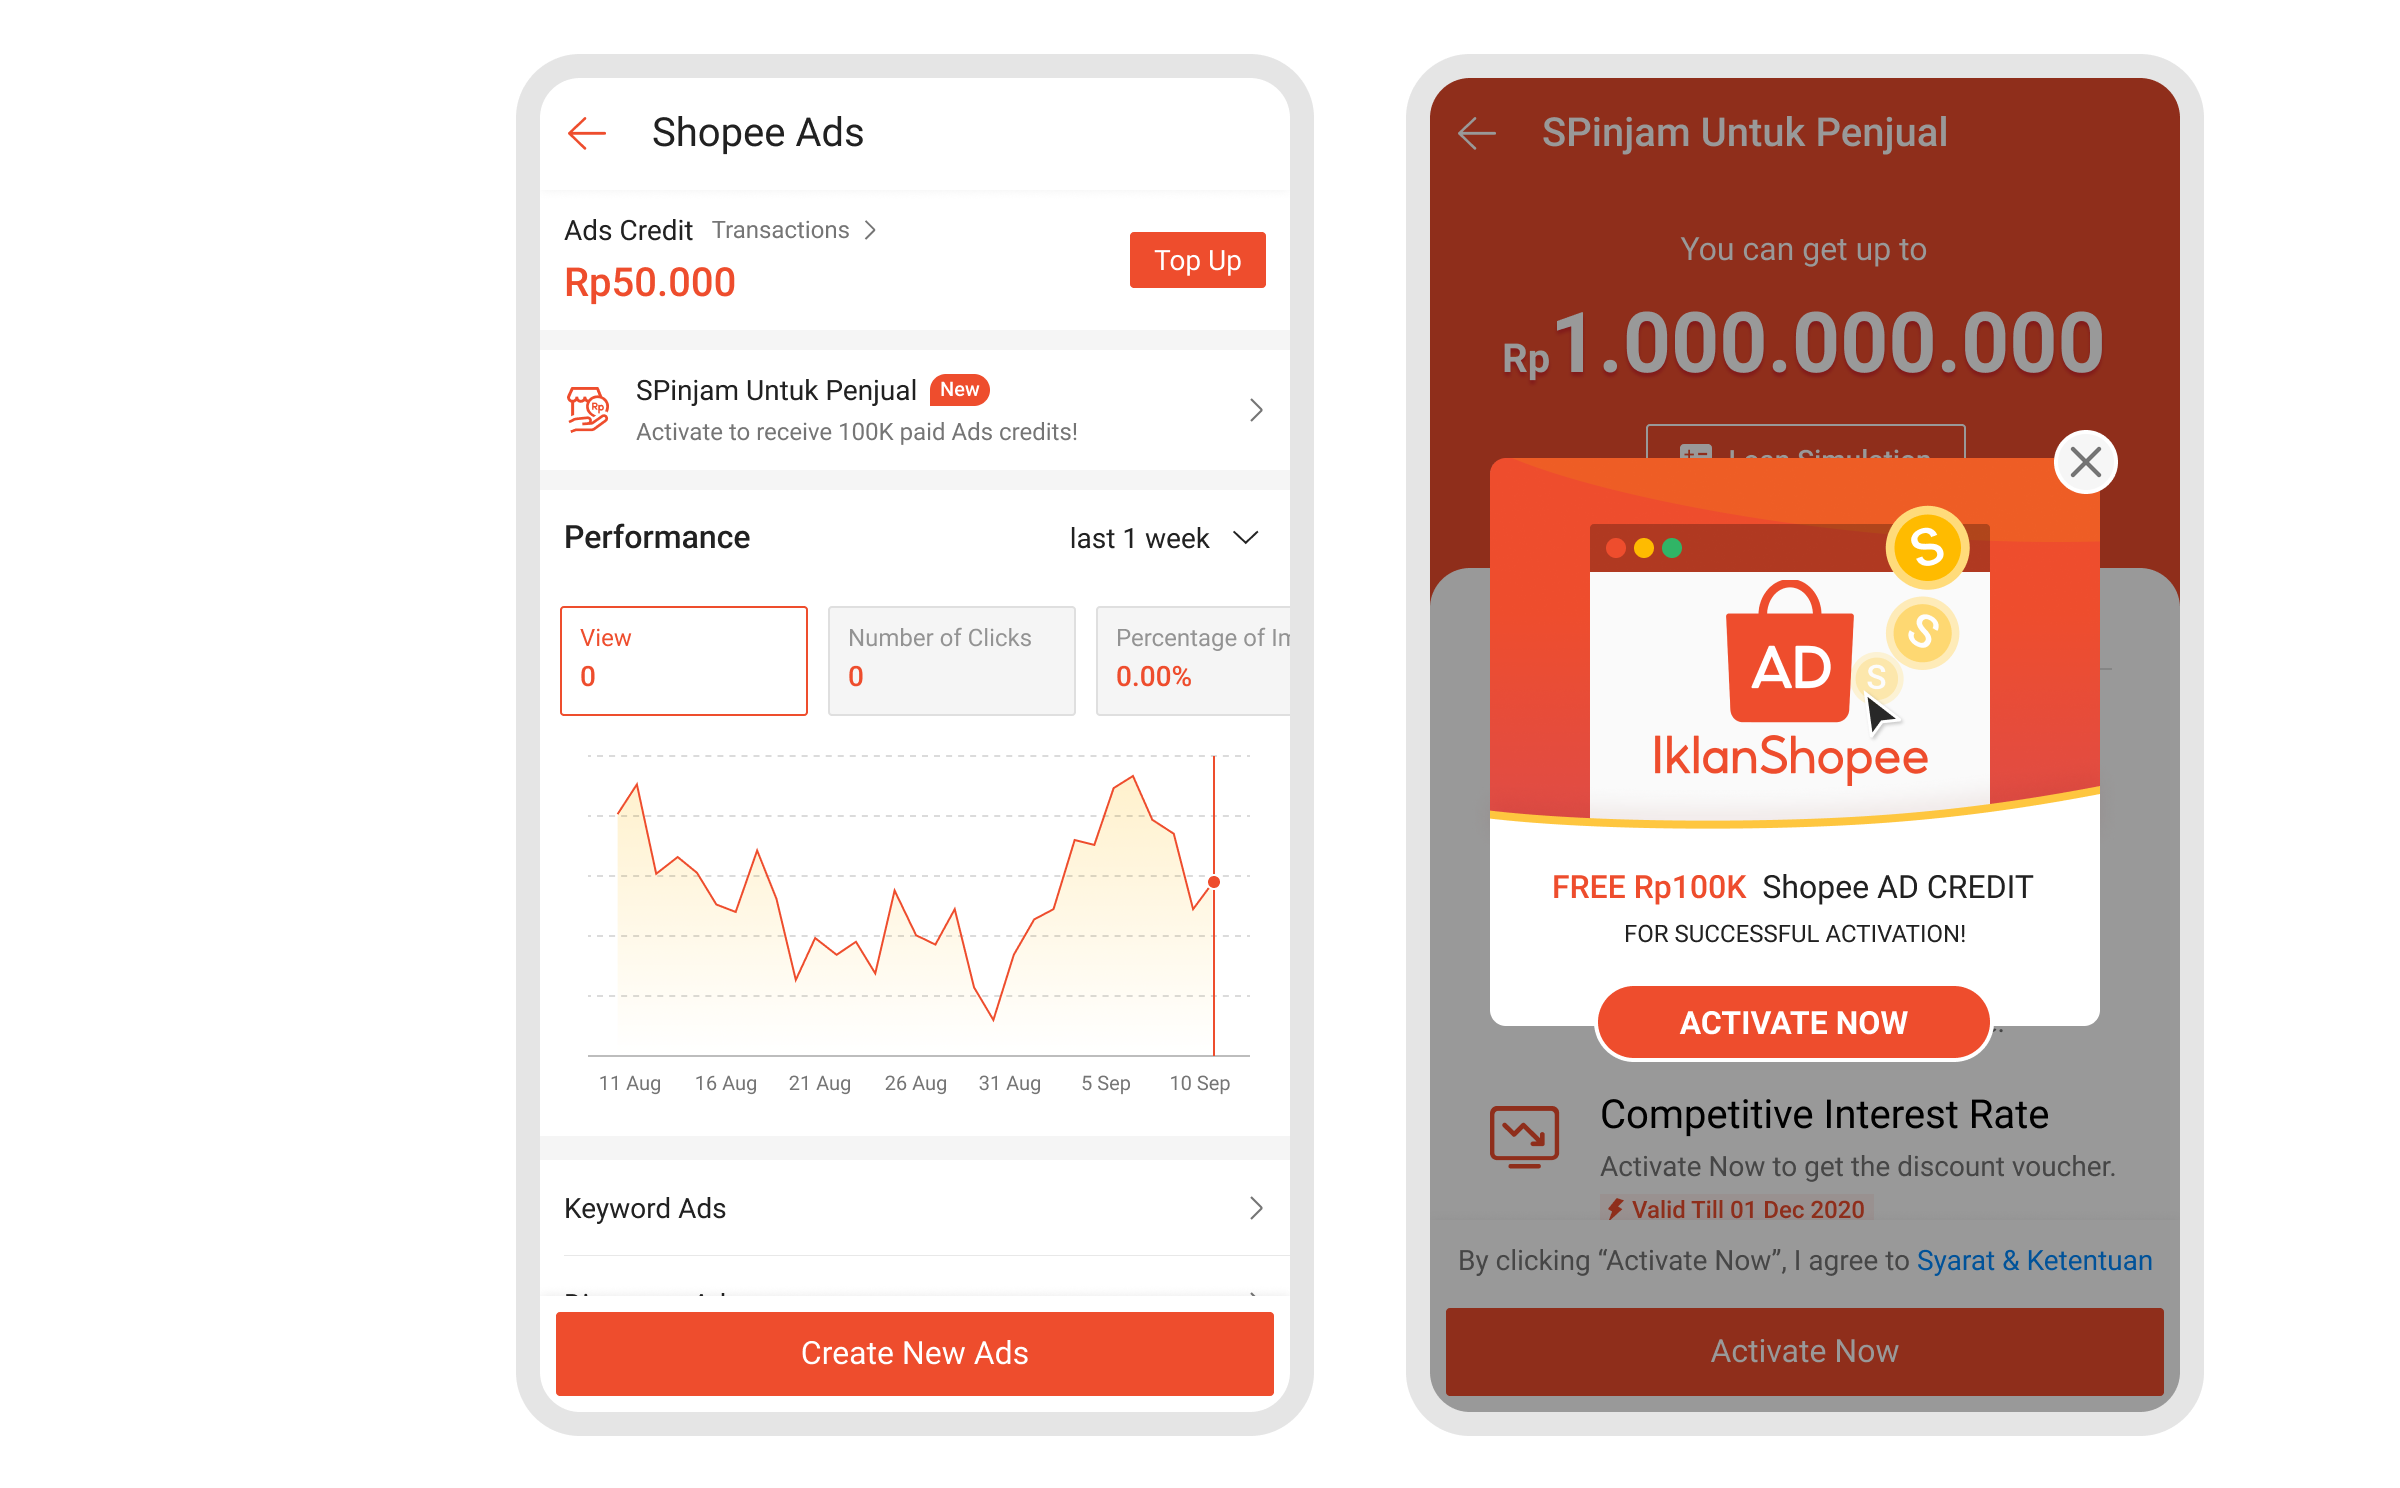
Based on data tracking, over 75% of loan sellers have accessed the paid ads landing page implying high cross-sale potential.
BI team has found an incentive mechanism for using Paid Ads to incentivize sellers to activate loans. On the other hand, loan sellers try ads service-free. If it works well, they can pay ads with loan disbursement afterward.
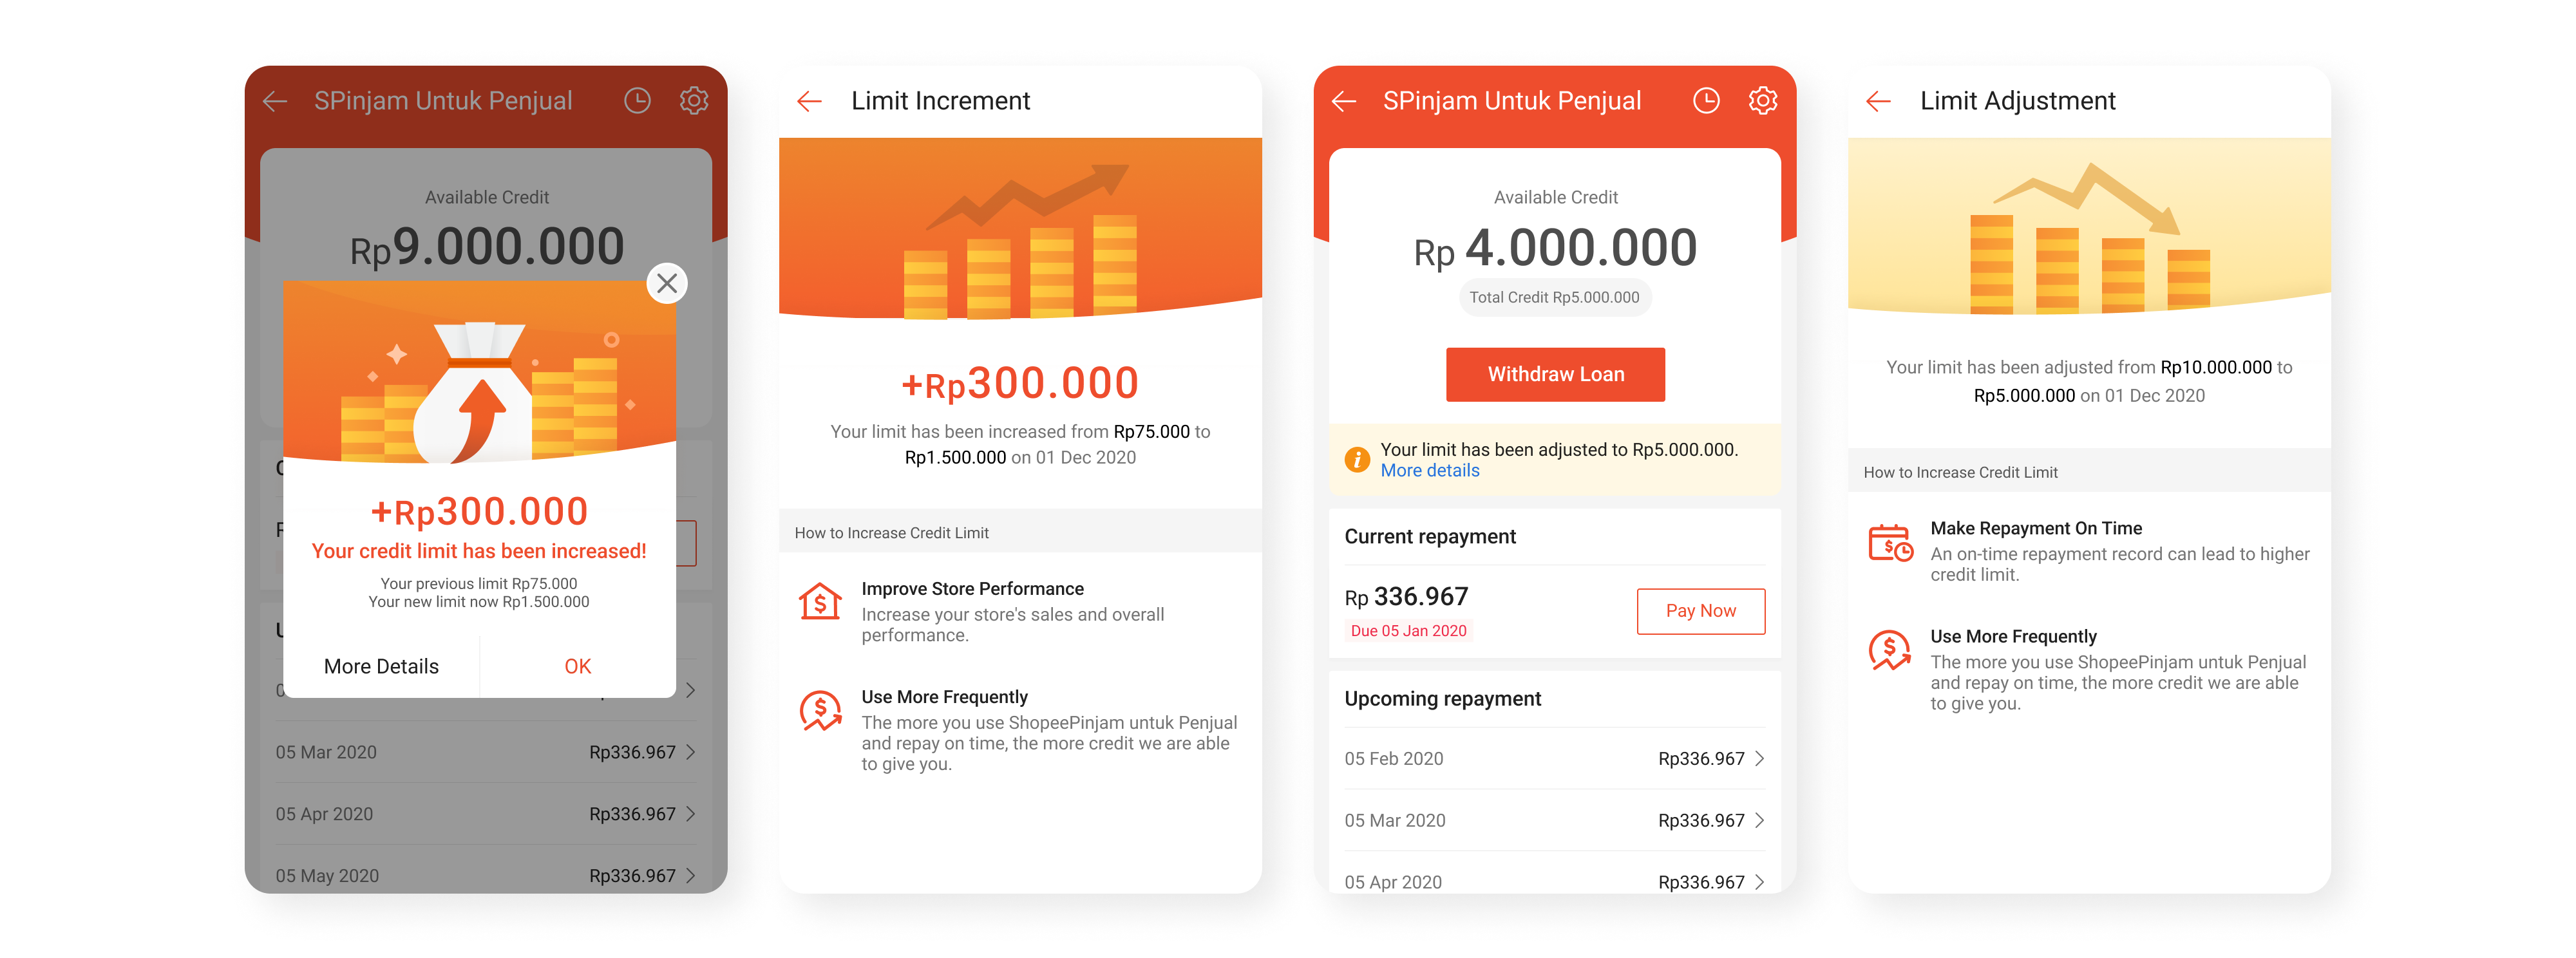
Before loan disbursement, each loan seller will have the related credit score and credit limit determined by Risk Engine. However, users' subsequent repayment habits will change and the previous limit may not accurately reflect assigned credit upon disbursement. Establish business logic to limit losses from high repayment risk users and to profit from low repayment risk users.
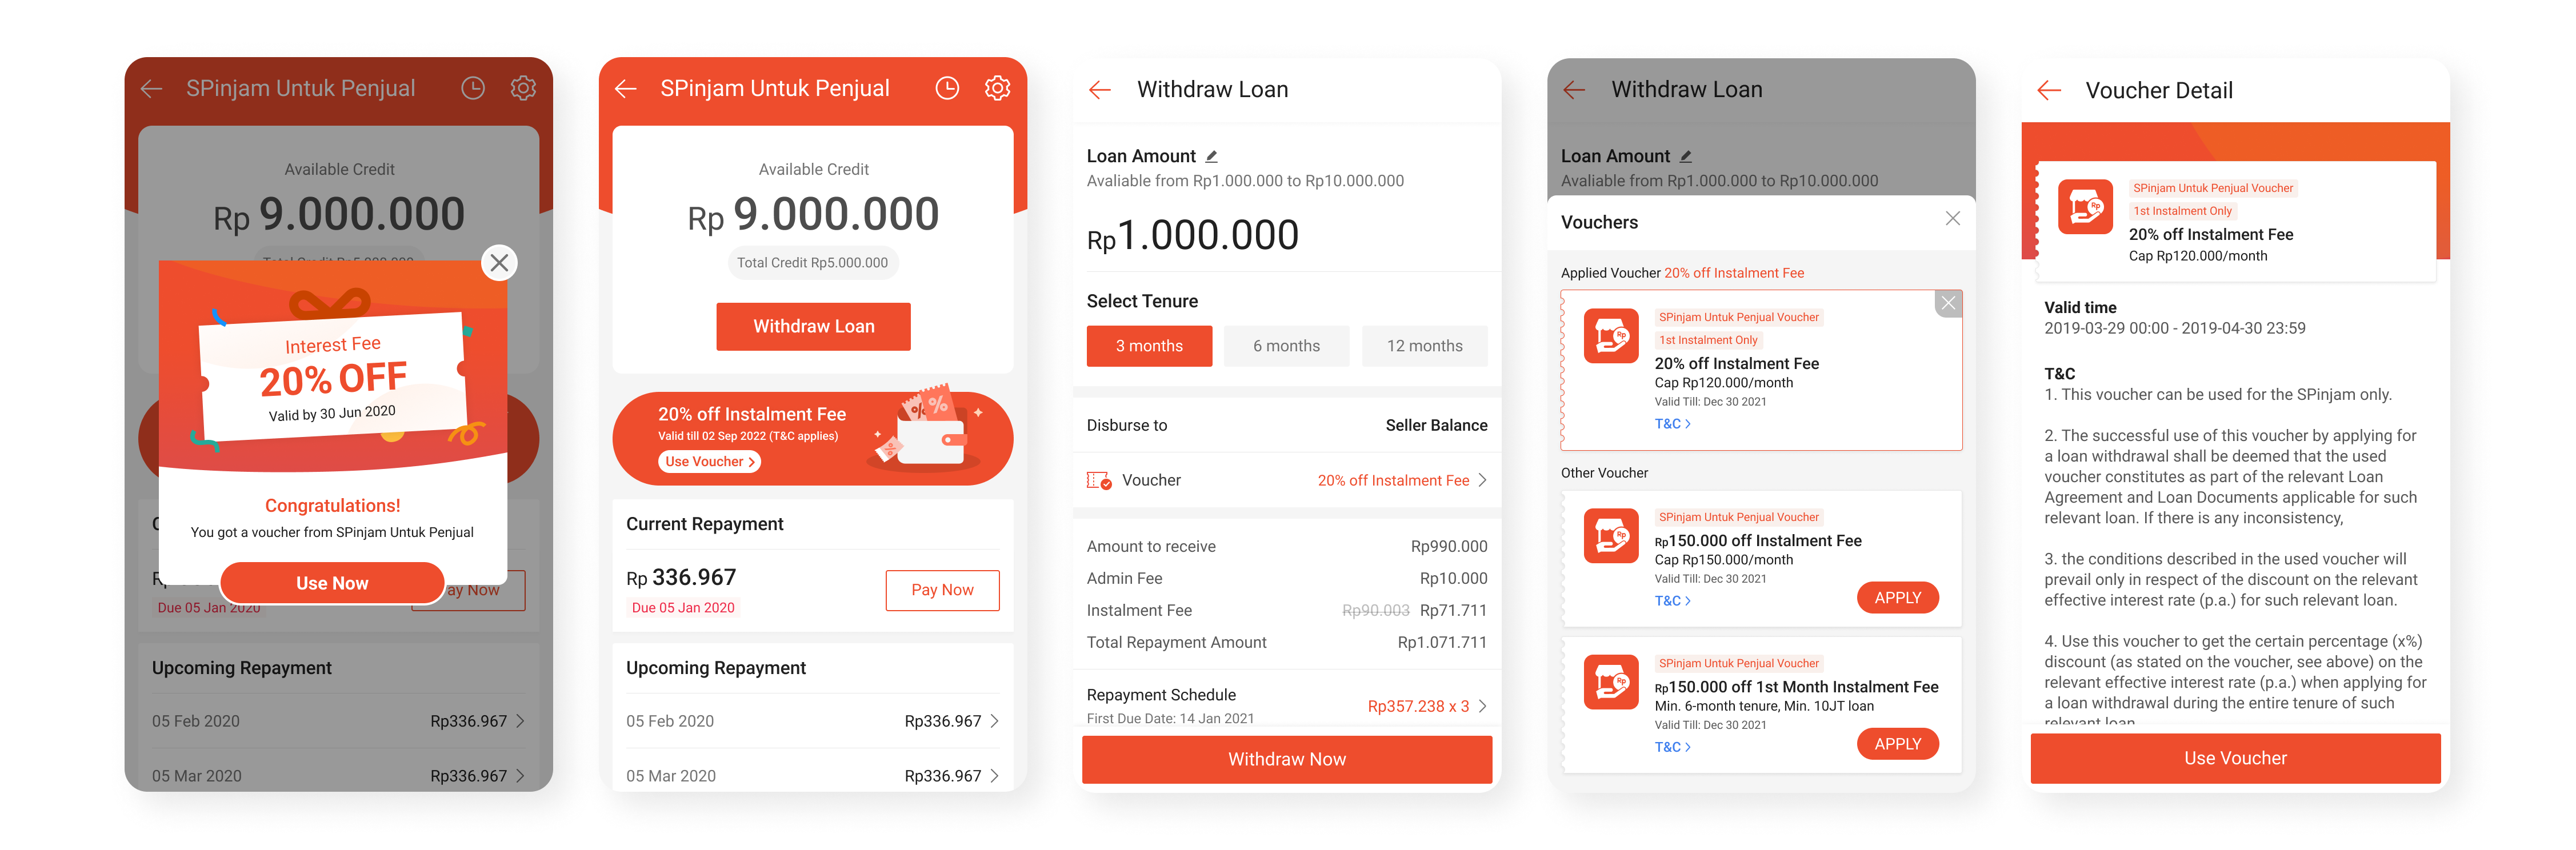
BD wants to improve the capabilities of the promotion system. The intricacy of voucher offerings can be more attractive and targeted used by user segments. Some types of vouchers can offer a discount but not incur too large a revenue loss. Some appeal to users who are insensitive to interest rates. Some can promote the uptake of longer tenure withdrawals and larger loans to increase loan outstanding over time.
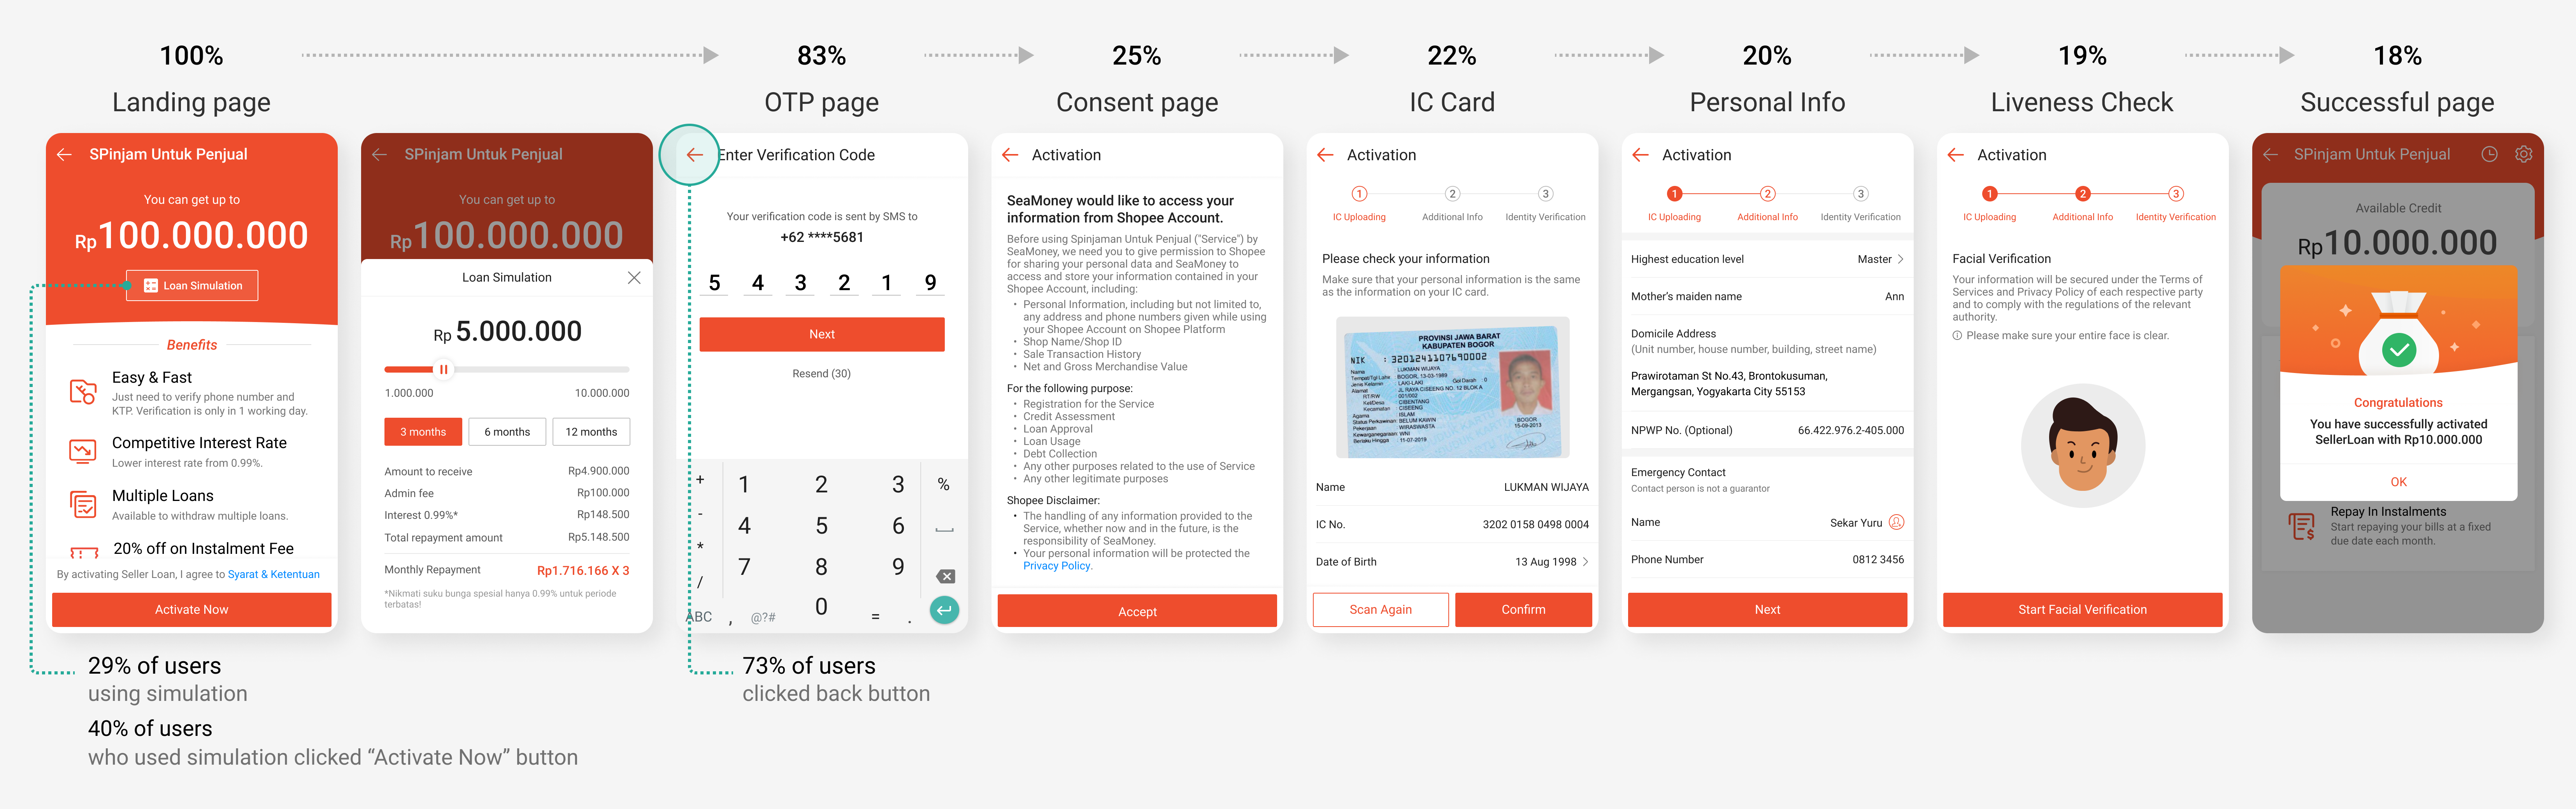
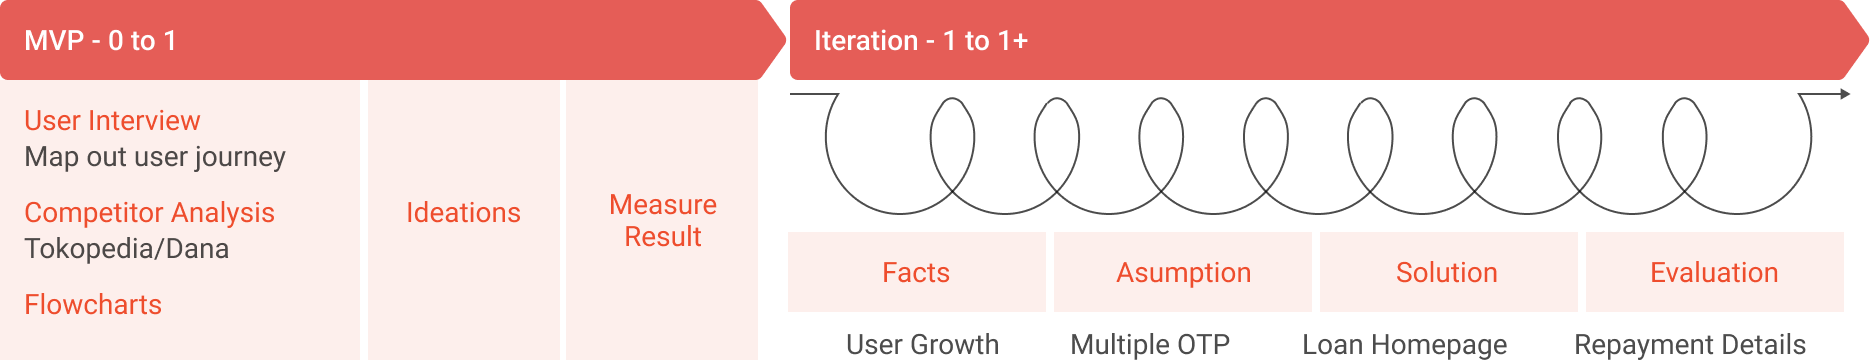
We focused on activation flow that gains acceptance among our target users in the market growth stage. We find the biggest drop-off takes place on the OTP verification page, especially the high back button click rate at 72%.
Through the investigation, we make a semi-informed assume that:
Users who failed to receive OTP may use weak signal telcomes.
Users are using a different phone number when activating their accounts.
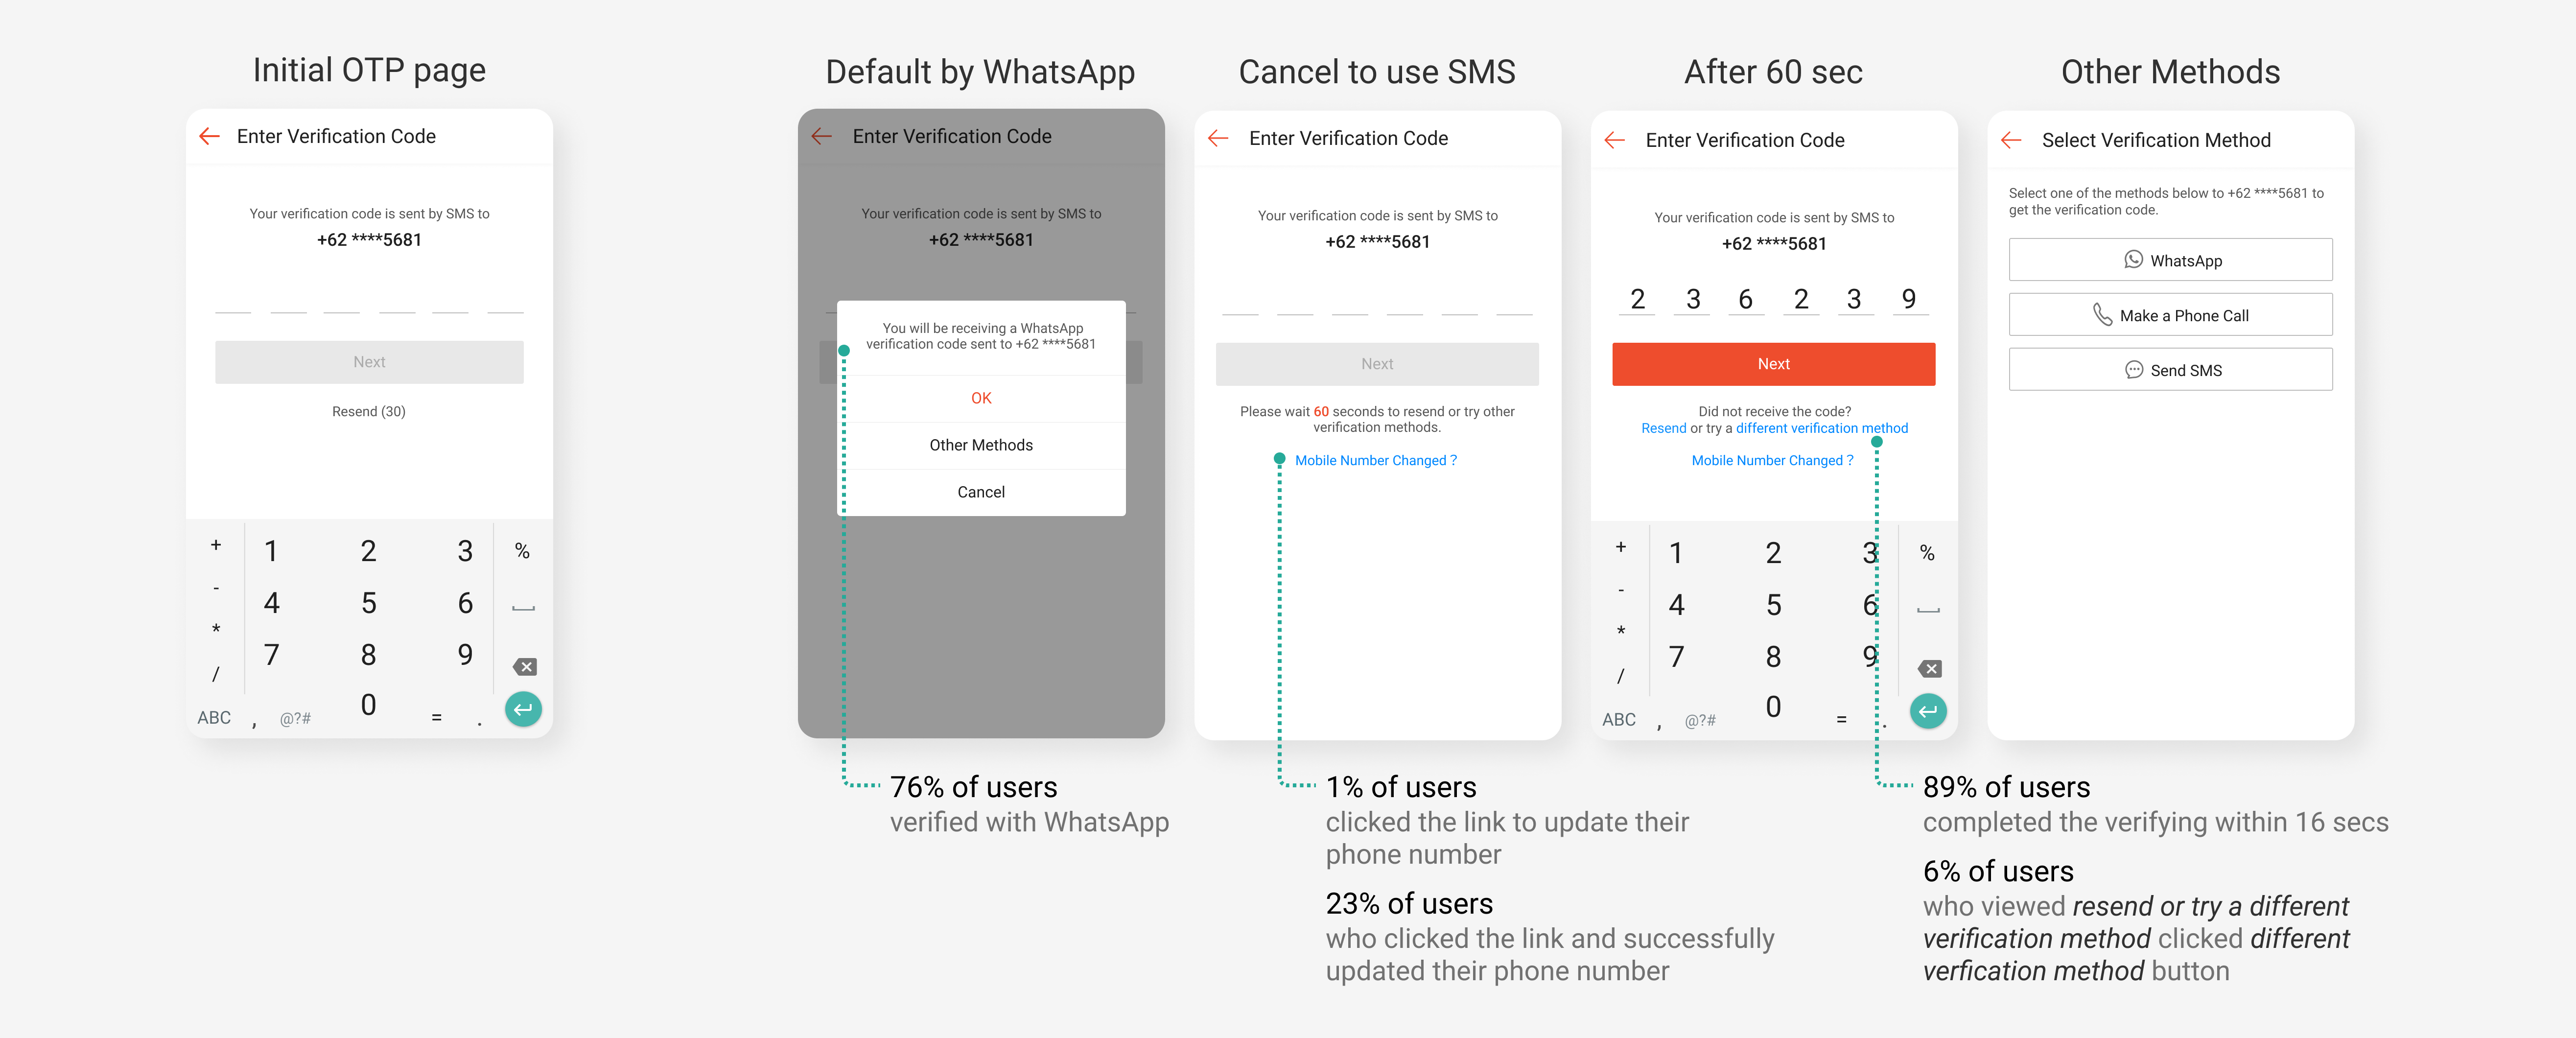
Based on the assumptions, we proposed the design solutions that
Add in Voice and WhatsApp as OTP methods to increase the OTP receiving rate. The reason for choosing these two alternatives is cost-saving. The unit price of Voice and WhatsApp OTP is almost 3 times lower than that of SMS OTP.
To see whether the solution is successful or not, we request event tracking while developing. Here are some findings and outcomes.
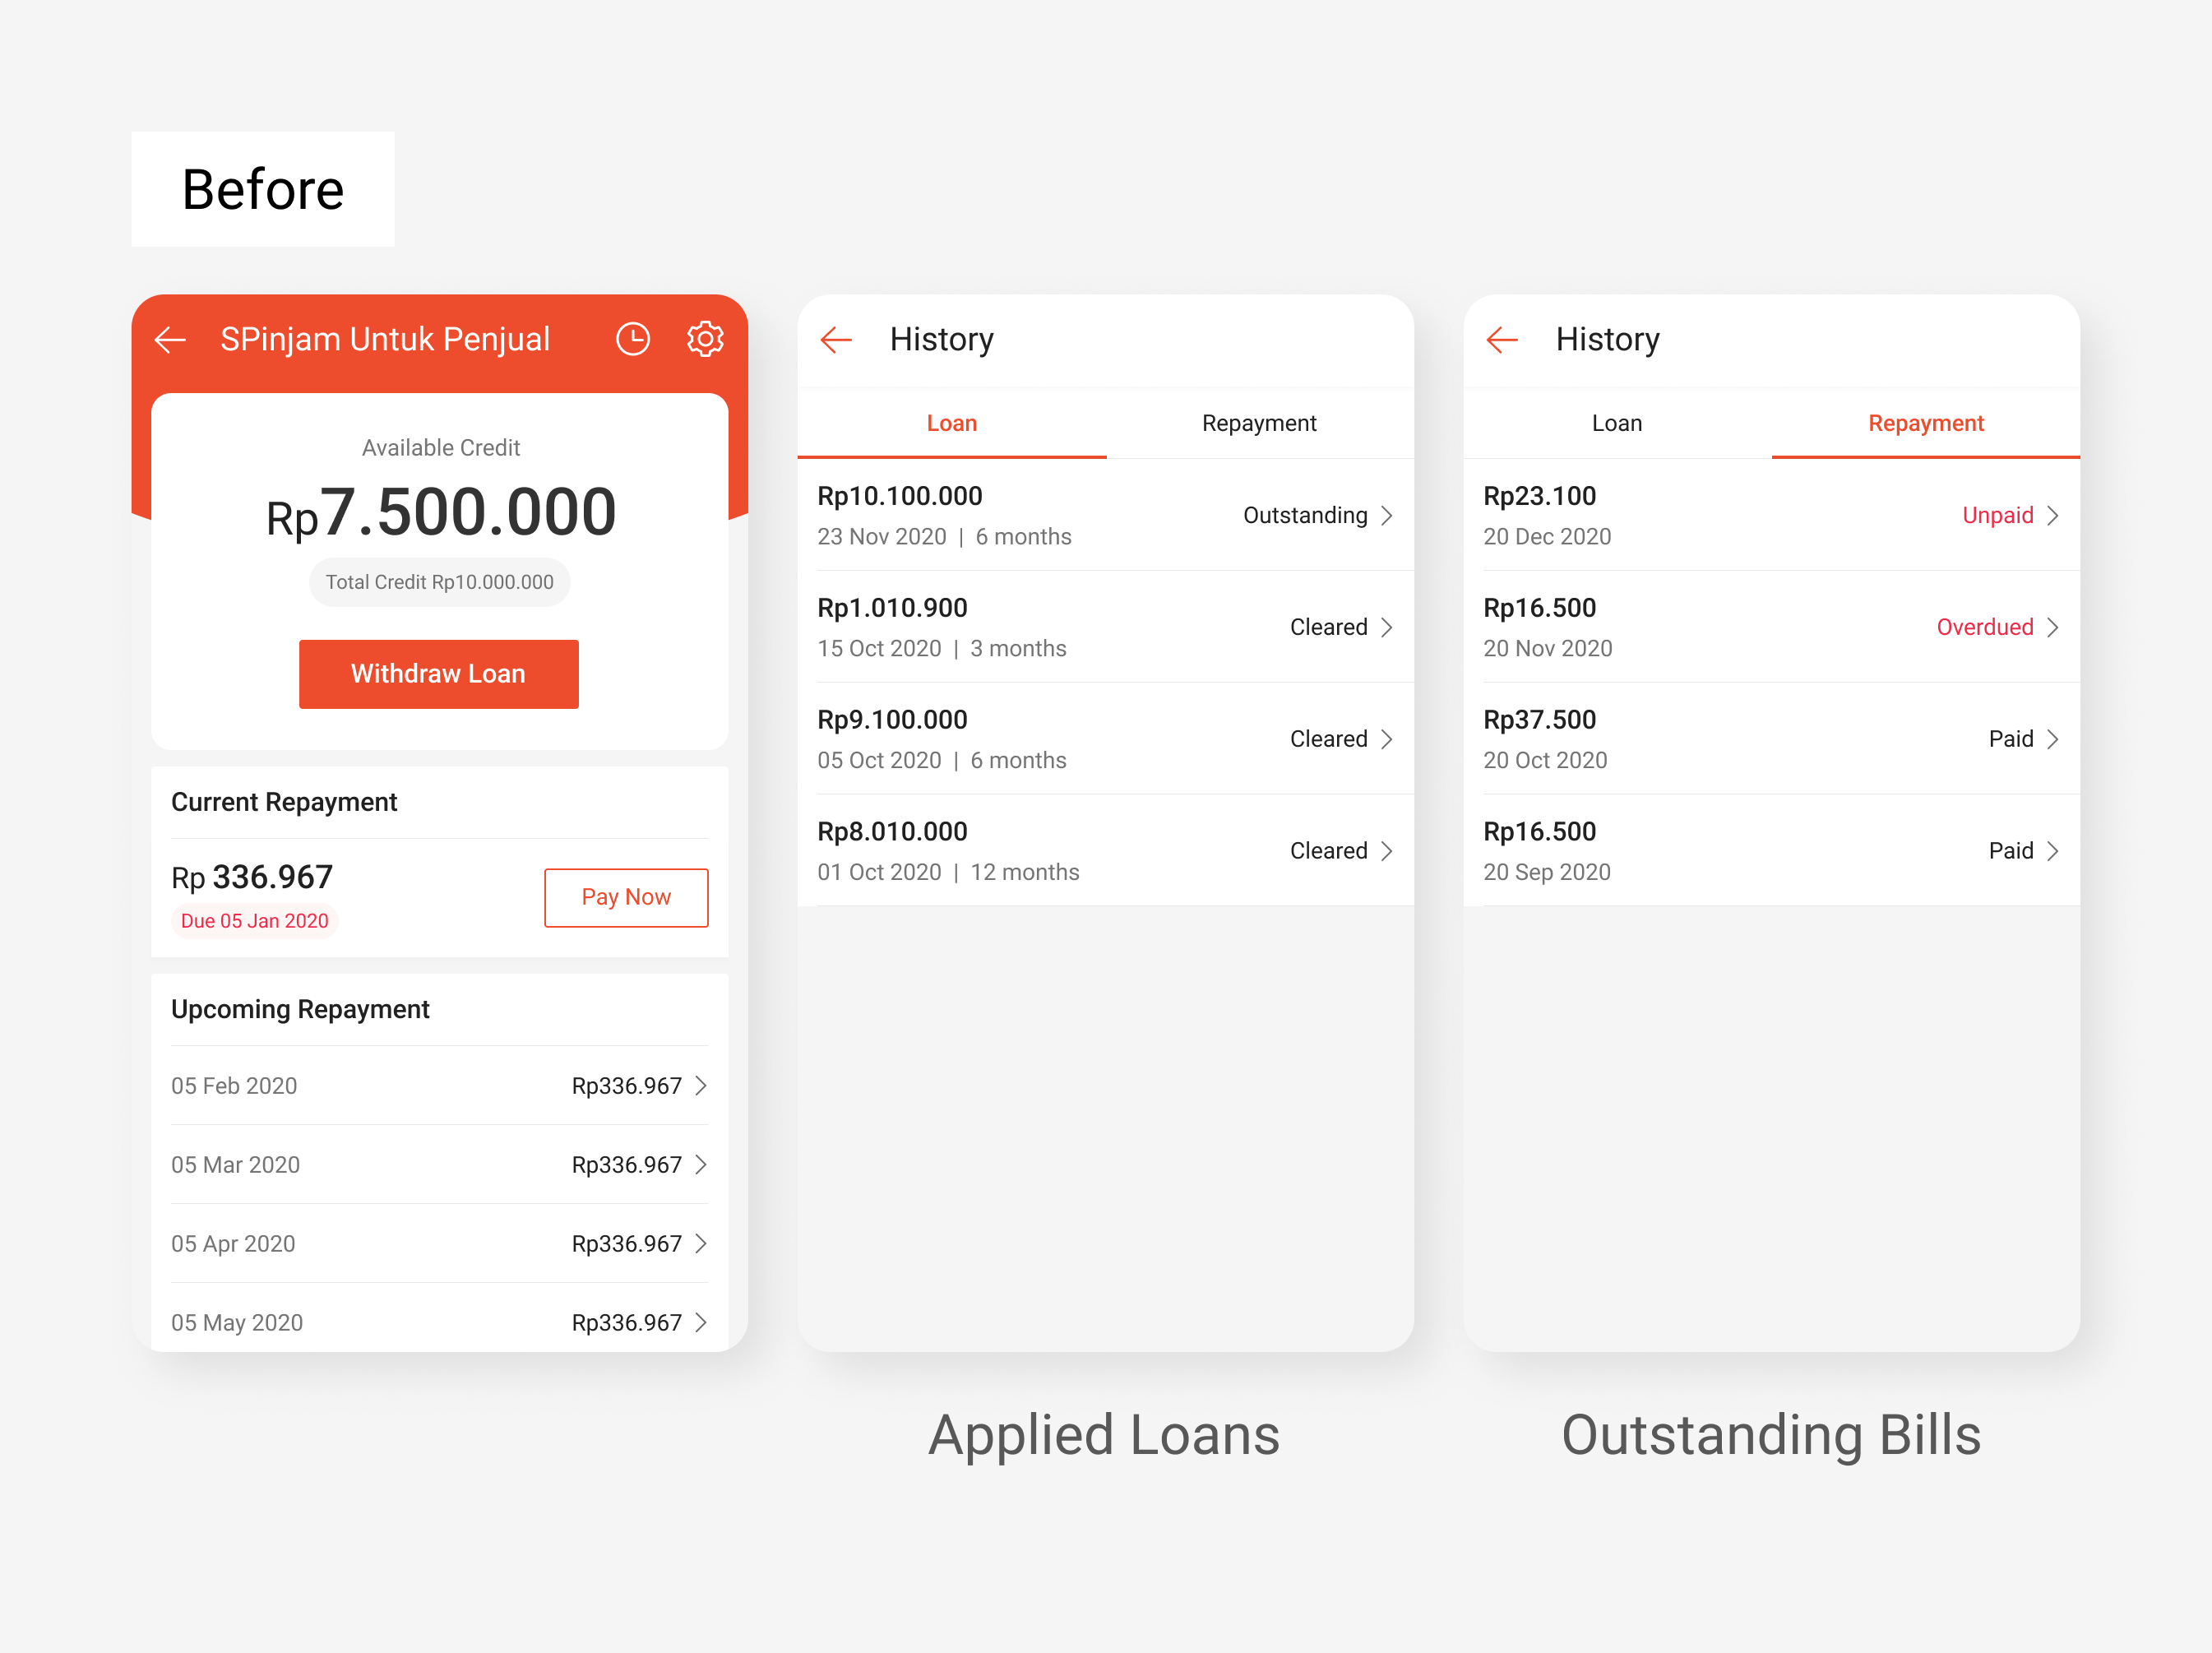
We found the CTR for upcoming repayment information is low on the home page but comparably high for ongoing loan information on the history page.
Usually, sellers owned multiple loans with long tenure at the same time. They care about the repayment that is about to due but not the following. We assumed that seller reviewed the repayment progress at the loan level instead of the bill level.
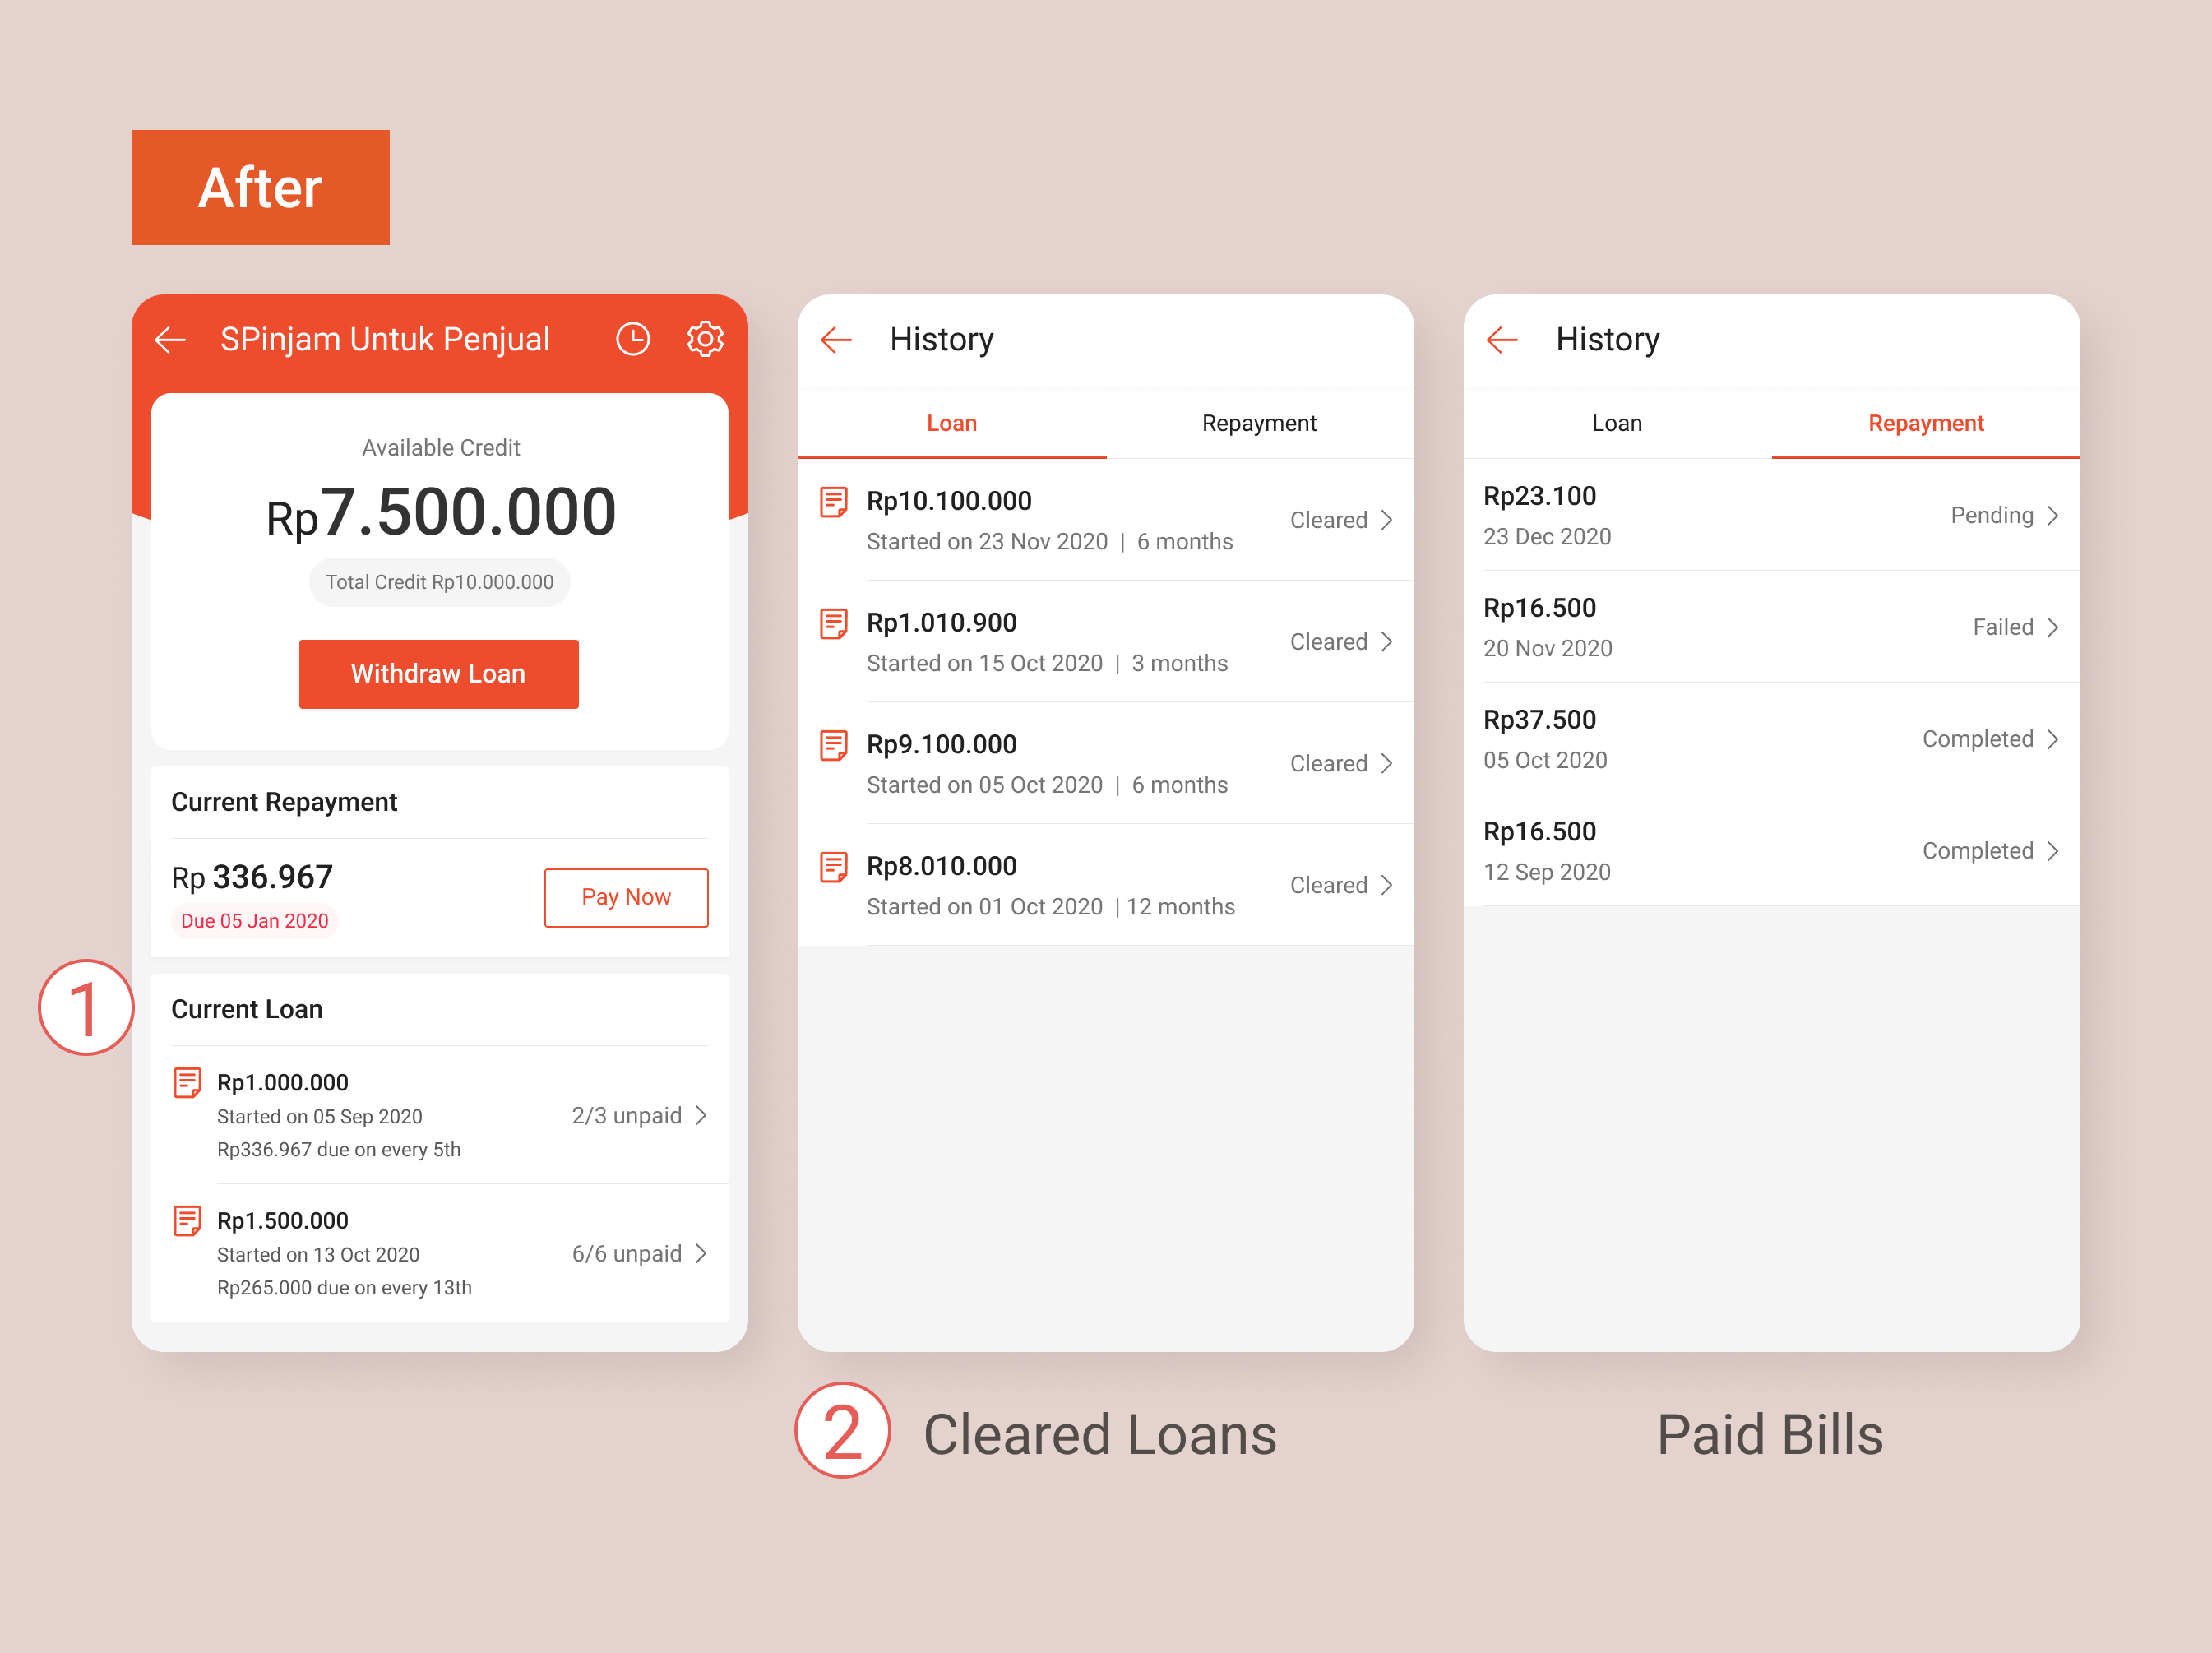
Based on the assumptions, we proposed the design solution:
Users identify each loan by its loan amount and applied time. So we describe loans by a chunk of loan details and put the repayment information.
Now the status of both loan and repayment is the end of the action on the history page.
New design increase CTR for the lower part of the homepage. Seller feedback that it is easier to use and got what they want than before.
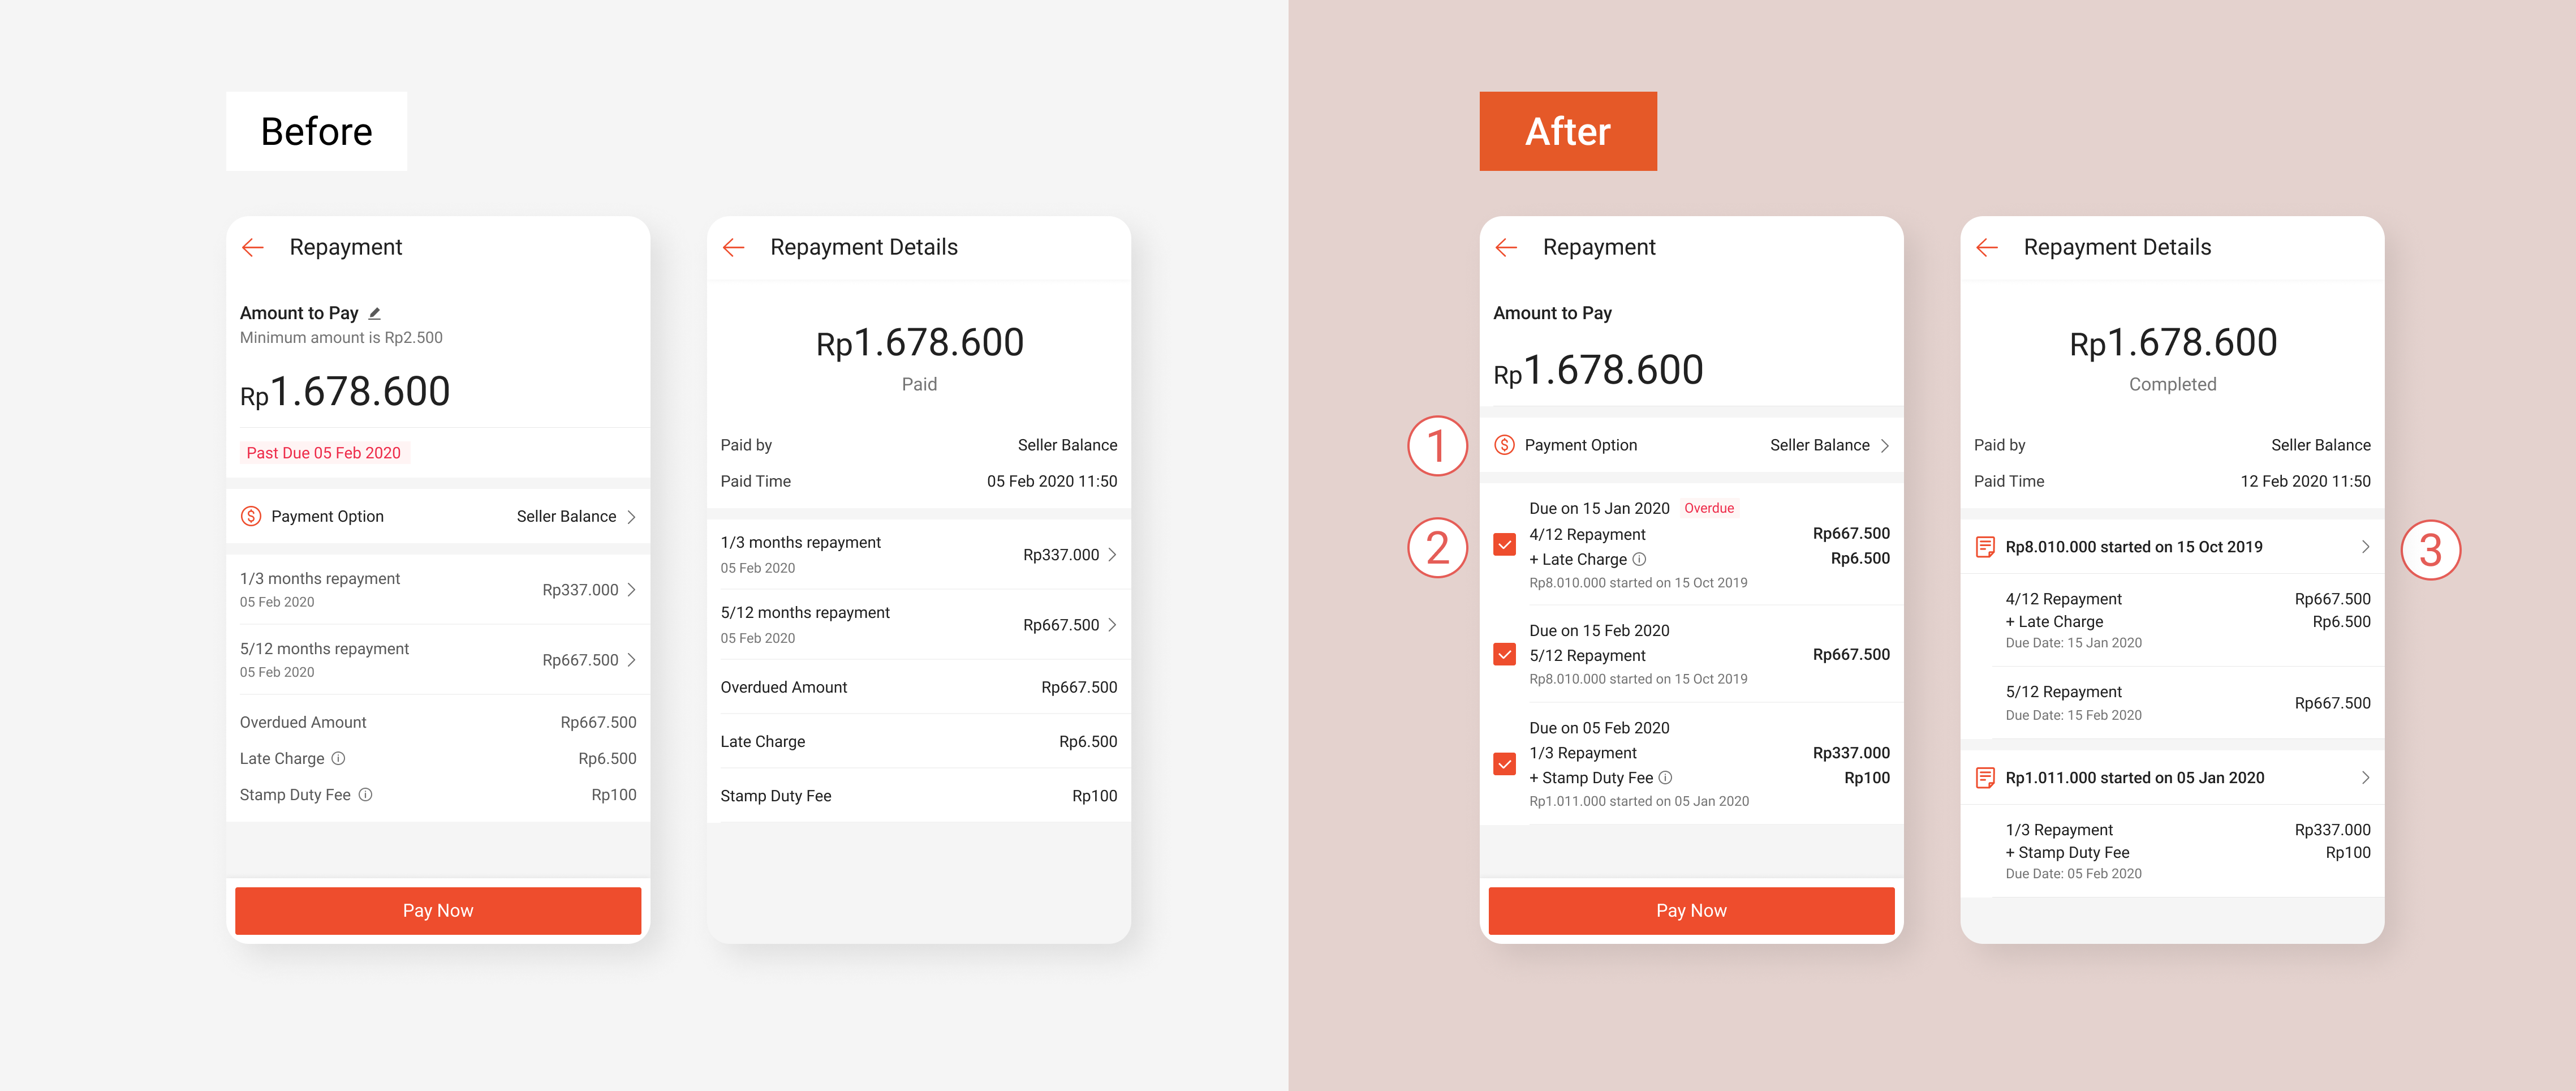
To integrate with other financial institutions for funding purposes, initially, all loans share the same due date every month, now it changes to each loan having its due date based on disbursement date.
This change impacts the structure of instalment. To avoid repaying the loan less than 1 month after receiving the loan, a few instalments will be consolidated into the current repayment and displayed on the frontend for users to repay together.
Instead of letting users input amount at will, we keep the repayment flexibility by allowing check or uncheck the checkboxes of instalments.
Be an MVP product, we streamline the details on the repayment page to launch it as quickly as possible. It is a chance to iterate the display based on the seller's habits.
First, we defined a particular loan by its loan amount and applied time. Second, we make the incurred amount relate to its insalment, such as the late charge fee and the stamp duty fee.
The partial payment was canceled, the payment details are displayed for the instalments.
Designing financial services has been an exciting and rewarding journey for me. It expands my domain knowledge in the financial industry and brings me a design perspective on building trust, anti-fraud, regulatory landscape, and more.
In the credit family, there are other likewise products, such as BNPL, Buyer Loan, and Retailer Loan. It comes the topic of design consistency. If users learn an interaction in one place, that knowledge can naturally transfer to the next. The benefit is not only for user experience but also for efficient development maintenance, which is about the system components and modules.
The challenge is about consistency that happens across countries of the same product and also between the series of products. Especially, different product lines are iterating at the same time. It's hard to design a shared module. The advantage of consistency should not be the design constraint. Therefore, I use consistency be a design principle. At the same time, I started to document the design assumptions for different countries which help me to review the design and tradeoff the decision.

